Thanks to my team and customers! #184 in the US!

Thank you to my hardworking team (Amanda Harvey, Camy Platt, and Michael Nardoni, and the entire support staff at Mortgage Trust)!  Furthermore, thank you to my customers and professional partners who place trust in our work!

I am happy and honored to announce that we ranked #184 in the entire United States for 2015 residential loan origination volume according to National Mortgage News.

orange metallic number 184 on white background.digitally generated image.
Thanks to everyone for their hard work and support. In 2015 we were ranked #184 in the nation for residential loan origination volume.

We look forward to continuing our service to customers in Oregon, Washington, and Idaho with professionalism and integrity.   Hopefully in 2016 we can march down that list!


Mortgage Rate Update March 7, 2016

Although mortgage note rates are unchanged from last Thursday pricing at these rates slightly worse.

Friday’s jobs report topped analysts’ expectations coming at +242,000 new jobs for the month of February.  Furthermore, as I thought may happen, previously released figures for December and January were reported higher.  As expected, mortgage rates worsened moderately following the better than expected results.

This week’s economic calendar is very light.  The highlight will come on Thursday when Europe’s Central Bank (ECB) meets.  Investors expect the ECB will lower short-term rates even further in an effort to boost liquidity into their economy.  As a reminder, the ECB’s current target rate is in negative territory which means they are actually charging banks to keep money on deposit.  Low rates overseas have helped keep rates low here in the US.

From a technical perspective we are keeping a close eye on the US 10-year treasury yield.  It is currently trading at 1.90% which is ~.20% higher than where we stood a couple weeks ago.  During that time mortgage rates have risen by .125%.
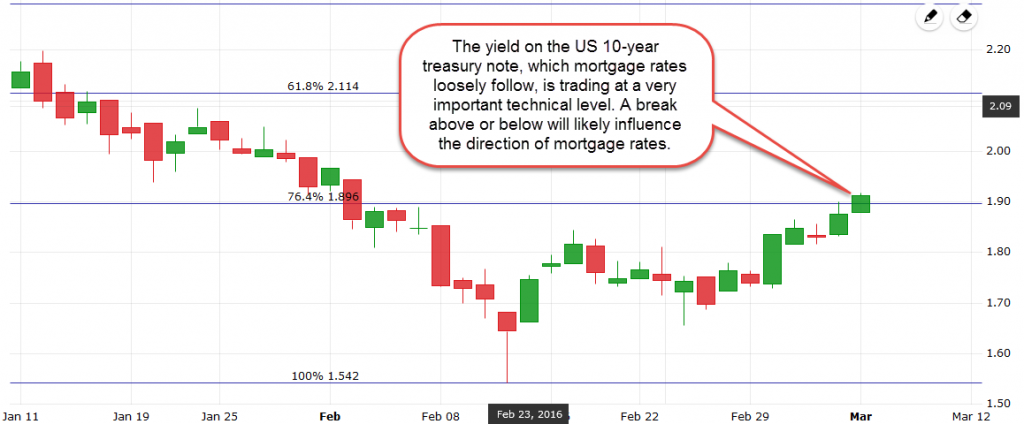
03-07-16-chart of yield mortgage rates portland ore

Should the yield break above this level it will likely creep higher by another ~.20% and we could expect mortgage rates to increase by .125%-.25%.  However, this level could also cause yields to reverse and trend back down.  If that happens I would expect mortgage rates to improve by ~.125%.

It’s a tough call.  I am going to shift my outlook to cautiously floating.

Current Outlook: cautiously floating
Mortgage Rate Update March 3, 2016

Mortgage rates are unchanged for the week.  That may all change tomorrow with the release of the all-important jobs report.

If you remember back to last month the jobs report missed expectations coming in at only 158,000 new jobs created.  This month analysts expect the report to show 190,000 new jobs created.  If the actual figure comes in higher than expected mortgage rates are likely to worsen and vice versa.

It’s always difficult to predict the monthly jobs report but based on what I am seeing I think there is more risk in floating than there is in locking.  Why?

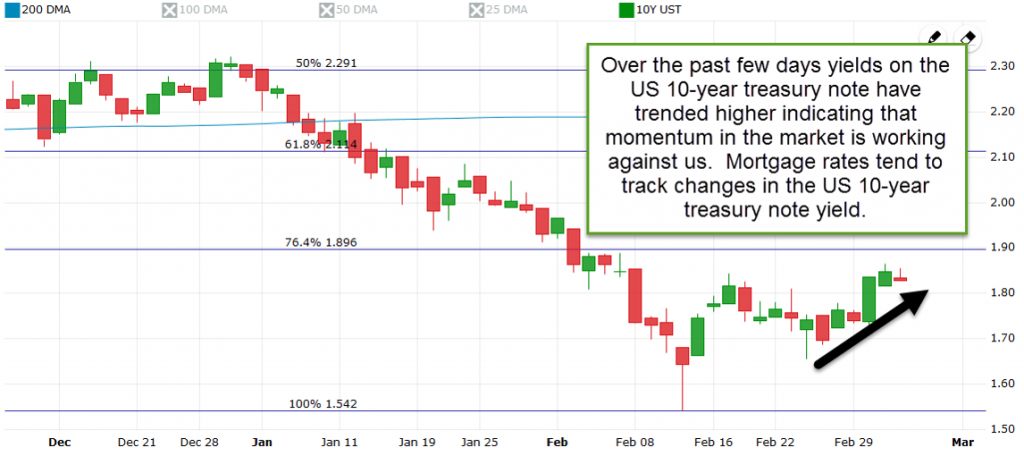
First, from a technical perspective momentum is working against us.  See the chart below.

03-03-US 10yr Mortgage Rates Portland Oregon

Second, recent domestic economic data has been relatively healthy.  Private Payroll company APD released its version of the monthly jobs report yesterday and it showed that 214,000 new jobs were created last month.  In a separate release, the Fed released a report which showed that consumer spending rose in much of the nation during the first part of the year.

Lastly, given that last month’s report was released well below expectations I believe that there is a greater likelihood that it will be subject to a revision higher which would put upward pressure on mortgage rates.

Current Outlook: locking

Comparing first-time homebuyers today to yesteryear?

Zillow’s real estate analytics blog released an interesting piece recently focusing on the characteristics of today’s first-time homebuyer.  You can read the entire piece HERE.  The author looked at a variety of financial and demographic trends of today’s first-time homebuyer and compared them to previous generations.  The findings?

A summary:

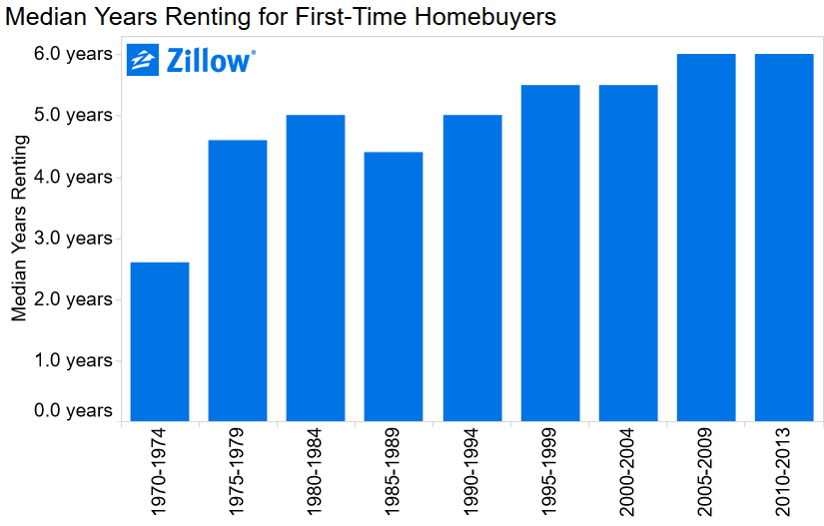
  • First-time homebuyers are older today and spend more time renting that previous generations.
  • First-time homebuyers are less likely to be married today than previous generations and increasingly purchase condo’s instead of single family homes.
  • Today’s first-time homebuyers have lower credit scores and down payments than previous generations.
Source: Zillow.com
Source: Zillow.com

The fact that homes are more expensive today relative to household income is likely influencing the findings.  How does your experience as a first-time homebuyer differ from your parents generation?  Please comment below.

Mortgage Rate Update February 29, 2016

Mortgage rates are similar or slightly worse compared to Thursday.

Interest rates here in the US continue to be influenced by international storylines.  China’s central bank announced today that it will cut reserve requirements on Chinese Banks in an effort to boost lending in their economy.  Asian stock markets reacted negatively to the news which provides support for the “flight-to-safety” trade that helps US interest rates remain low.

In a separate release inflation figures out of Europe were reported very low earlier today.  The report makes it more likely that the European Central Bank will expand its quantitative easing measures when they meet again in March.  That expectation will encourage demand for US dollar denominated assets and make it harder for US interest rates to increase.

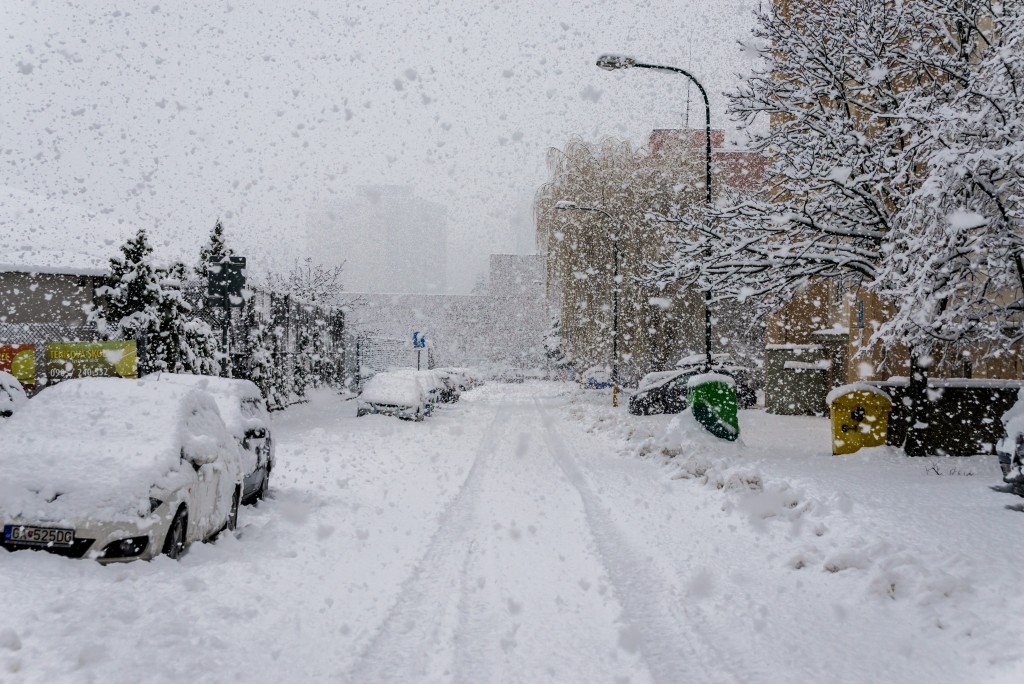
In domestic housing news the National Association of Realtors released its monthly pending home sales report.  It showed the numbers of homes pending in the US declined last month but is still 1.4% higher than a year ago.  Harsh weather on the east coast and lack of supply were credited with the decline.

Harsh winter weather on the east coast is being blamed for lower pending home sales in January.

Looking ahead it is jobs week and the rest of the economic calendar is busy.  From a technical perspective mortgage rates look safe so we’ll maintain a floating bias.

Current Outlook: floating bias

Mortgage Rate Update February 25, 2016

Mortgage rates are similar or slightly better compared to Monday.

China’s stock market plunged for the second time this year.  The Shanghai Composite Index fell by 6.4% today as investors showed concern for the state of the Chinese economy.  The volatility in China has redirected capital into the US debt markets which helps rates move lower (click HERE to learn how).

In case you missed it Portland led the country in year-over-year home price appreciation according to the latest Case-Shiller Home Price Index report that was released on Tuesday.  According to the report home prices rose by 11.4% from December 2014 to December 2015.  Some onlookers have begun to ask if a bubble is forming here in Portland.  Click HERE to see why we’re not there…..but not ruling it out in the future.

Case-Shiller Home Price Index- Portland, OR

In other housing data, the National Association of Realtors NAR released monthly data on existing home sales.  Nationally home sales increased to a 6 month high.  However, the number of home sales actually decreased in the West Region from December to January (still higher on a year-over-year basis).  A lack of supply was blamed.

NAR chief economist Lawrence Yun commented, “The spring buying season is right around the corner and current supply levels aren’t even close to what’s needed to accommodate the subsequent growth in housing demand.”  You can say that again.

From a technical perspective the outlook looks modestly positive.  I will shift to a floating bias.

Current Outlook: floating bias

Making Your Offer as Competitive As Possible

If you are a prospective homebuyer in the Portland housing market then I don’t need to tell you how competitive it is. The most recent Case-Shiller Home price Index showed that Portland leads the nation in year-over-year home price appreciation and a separate study released by United Van Lines showed that we lead the nation in attracting new residents.

The impact in our housing market is that there is very strong demand and not enough supply to accommodate it. These conditions will likely evolve over time but for now it is making it hard for homebuyers to compete.

I will be writing a series of posts that will outline strategies a prospective homebuyer can do to optimize their chances in having their offer accepted by a seller.

Here are the topics I will be covering:

  1. Completing & Communicating a comprehensive pre-approval
  2. Know your limits
  3. Accommodate the sellers’ timeline
  4. Eliminating a home sale contingency
  5. Buy the home then do the mortgage
  6. Avoid FHA & VA
  7. Let the lender pay your closing costs

Do you have any ideas for getting your offer accepted? Please comment below.

Is there a bubble forming in Portland?

As those of us in the Portland, OR housing industry know the current imbalance between supply and demand in our local market is a little bit concerning.  Stories of multiple offers, waving contingencies, and sales way above asking are everywhere and for some the prospect of buying a home may seem impossible.

Fortunately, I am hearing from Realtor professionals that they are getting more and more inquiries from sellers as we move into spring.  This is a welcome sign because greater supply is the only thing that will ease the existing pressures.  Portland is a very desirable place to live and we expect demand to remain strong.

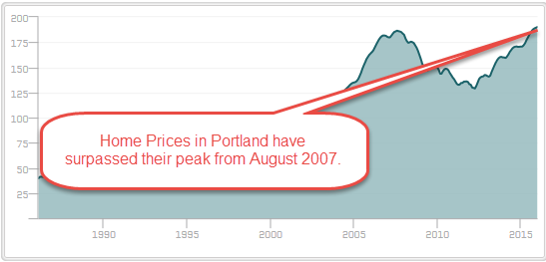
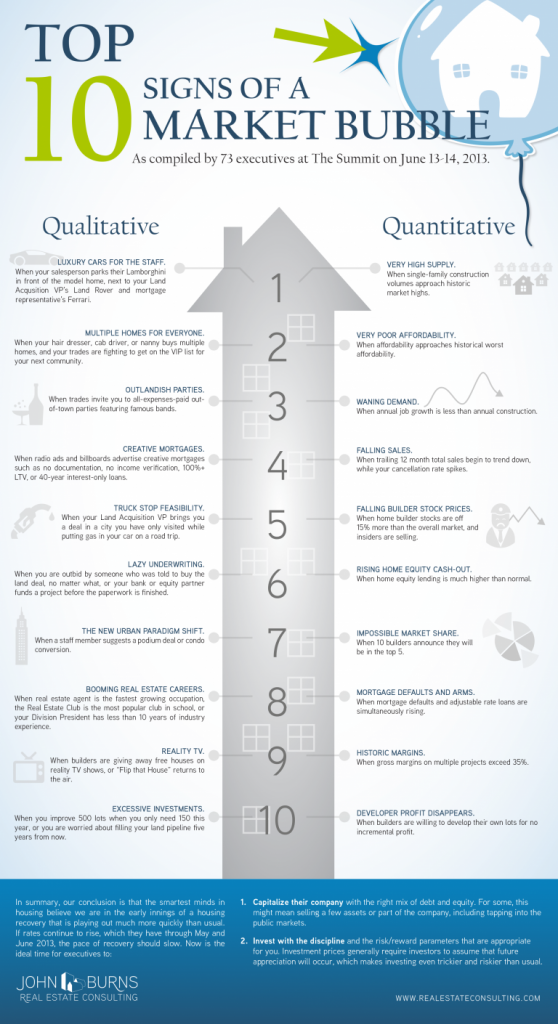
That said, I have heard some participants voice concerns about a real estate bubble brewing.  I thought I would share an info-graphic that John Burns released last week on his blog:

Is-There-a-Market-Bubble-in-Potland-OR
Click Here to view post

At this point I do not forecast a bubble popping in Portland.  Demand remains very strong and the outlook for jobs in our area looks solid.  As long as there is a lack of supply I don’t see how prices can fall.  Should those dynamics change in the future, which is entirely possible, then I would have to adjust my forecast.

What are your thoughts?  Please feel free to comment.

Mortgage Rate Update February 22, 2016

Mortgage rates are unchanged from the latter half of last week.

Friday’s Consumer Price Index (CPI) report from the Bureau of Labor Statistics suggests that the Fed may have to get back on the path of hiking rates.  The report showed that the Core CPI, prices for consumer goods excluding food and energy, rose by 2.2% on a year-over-year basis.  This is the “hottest” figure since June 2012 and above the Fed’s target of 2.00%.  Inflation is the primary driver of long-term interest rates including for home loans.

Is inflation ahead?  If so, it would pressure mortgage rates higher.
Is inflation ahead? If so, it would pressure mortgage rates higher.

This Friday we’ll get the Personal Consumption Expenditure price index which is the Fed’s favorite gauge for inflation.  If that also comes in higher than expected then it would likely pressure mortgage rates up.

Looking at the rest of the economic calendar this week the Case Shiller Home Price index is due out tomorrow.  We’ll also get readings on consumer confidence and existing home sales.  On Wednesday the FHFA will release their home price figures and on Friday we’ll get the 2nd estimate for 4th quarter 2015 GDP.  I wouldn’t be surprised to see some volatility this week given the depth of data scheduled for release.

From a technical perspective mortgage rates are trading within a ~.125% range.  I don’t necessarily see a catalyst for rates to improve in the near-term but I also don’t see them increasing so I will shift to a neutral position.

Current Outlook: neutral

Mortgage Rate Update February 18, 2016

Mortgage rates are unchanged from Monday.  Mortgage rates remain slightly worse as compared to last Wednesday-Thursday.

US stocks started the day higher but have since stalled, which bodes well for interest rates.  Worries over slowing global growth have re-emerged which drives capital into perceived “safe-havens” including the US debt markets and drives our yields lower.

Is the US economy on the brink of an economic slowdown?  The Philadelphia Fed released its monthly barometer for manufacturing and it remained in negative territory which signals continued contraction for manufacturing.  Bad news for the economy tends to be good news for mortgage rates.

Continuous weakness in the manufacturing sector has some investors worried.

Tomorrow we’ll get the latest reading on the Consumer Price Index (CPI).  Inflationary pressure remains weak in our economy (exception: housing costs in Portland, OR) and we’ll see if that trend continues. If so, that fact coupled with fears over an economic slowdown will put the Fed on hold in hiking short-term interest rates.  The next Fed monetary policy meeting is scheduled for March 15th-16th and the markets think there is a 94% chance the Fed will not hike.

From a technical perspective there is reason to believe that mortgage rates can regain the .125% they lost late last week so I am going to recommend cautiously floating.

Current Outlook: floating