Rates end Q1 on a positive note but higher rates likely later in the year

At the end of her life my wife has already decided to be buried at the golf course so that I visit her multiple times per week.  It’s’ Masters week which means my productivity at work will decline significantly starting Thursday.

Quarterly Report

Interest rates had a tough start to the year increasing by approximately .50% during the first seven weeks.  Peaking on February 21st mortgage rates have since flattened and even improved modestly.

For the quarter mortgage rates increased by about .375%.

Yield Curve

The yield curve is at the flattest point since 2007.  The yield curve measures interest rates over a variety of durations.  The chart below depicts the difference between the yield on the 2-year and 10-year treasury notes.  As the difference declines the yield curve gets flatter.
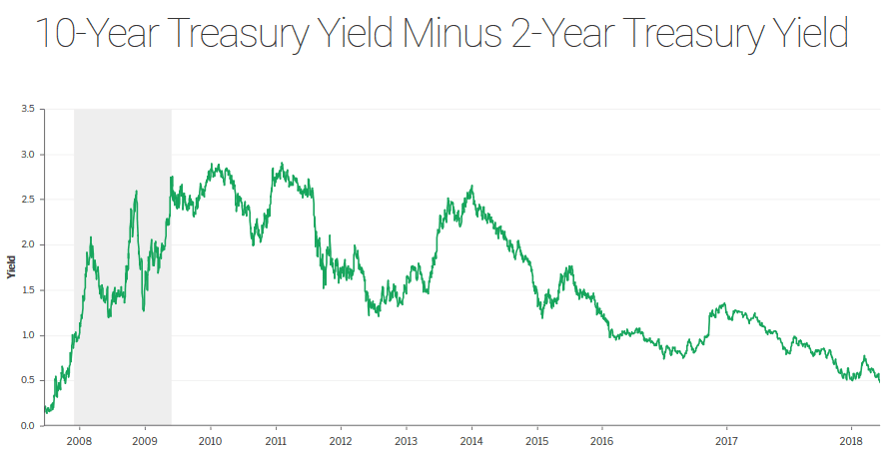
A flat yield curve is thought to forecast either an economic slowdown or higher long-term interest rates in the future.  Given that the economy appears to be stable I think we are in for higher mortgage rates later in the year.

US Stocks

Home loan rates are currently benefiting from volatility in the US stock market.  Equities are off ~2% again today as investors fret over the possibility of trade wars with China and regulatory backlash on tech companies.  When stocks do poorly interest rates tend to benefit.

The Week Ahead

It’s the first week of a new month so we’ll get the all-important jobs report this Friday.  Analysts are most interested in average hourly earnings which has remained sluggish despite low unemployment.  A higher reading for hourly earnings would be unfriendly to mortgage rates. The remainder of the economic calendar is light.

Mortgage rates are presently at the lower end of their recent range so I will recommend locking.

Current Outlook: locking
Don’t get scammed by a mail-order mortgage company!

Video Transcript:

Hey guys, Evan Swanson here to talk to you today about something that drives me crazy. That is phone and mail solicitations on mortgages.

As a mortgage professional, I get them just like you do. The only difference might be I have a little easier time navigating and understanding the information they’re trying to share. I can tell you, 99 times out of 100, these companies don’t care about your financial well-being. They are only interested in making a commission and doing the transaction.

Example, here’s a solicitation my wife and I received recently. Understand, I don’t mind telling you that we locked our rate in at a few years ago. We have a 3.50% 30-year fixed rate mortgage. This company is telling us that we could refinance and get cash out of $41,000. It’s telling us to refinance into a higher interest rate than we currently have. It’s telling us that we can eliminate our mortgage insurance.  Yet, we don’t have mortgage insurance. It’s also telling us here that no equity is required to make the loan.

However, if you flip over to the back and read the small print it says “30-year term conventional loan with a minimum of 20% equity.” Wait a minute. I thought you said there was no equity required?

Here’s another solicitation a colleague of mine got who currently has a 2.50% fixed rate mortgage on their house with 18 years left. Their own mortgage company is soliciting them to try to refinance into a 30-year term at 5.25%, and then it’s telling them they can expect to save money annually. I’m sorry, but if you take a 2.50% fixed rate and turn that to a 5.25%, there is no savings. There may be cash flow savings because they’re spreading their payment of principal over 12 additional years, but that’s not savings to the customer.

Bottom line, guys, if you’re interested in getting your house looked at for refinance, don’t go with one of these solicitation companies. They don’t care about your financial outcome. They’re only interested in their own well-being.

Contact your local mortgage broker today. Talk to someone who knows what they’re doing and will give you a fair assessment of your options.

Of course, I would love to make myself available to you.  Please contact me today!

Stocks slide and mortgage rates hang steady

If you’re like me then your NCAA men’s basketball bracket is officially busted.  With two #1 seeds eliminated in the first weekend I will now focus my sporting attention on the upcoming Masters golf tournament.  Speaking of golf, do you know why Virginia and Xavier fans only plan 14 holes? They can’t make it to the final four.

US stocks slide

US stocks fell by approximately 1% last week and are down sharply again today on news that data from Facebook may have been breached in 2016 and improperly used by a third party vendor in the presidential election.  Facebook shares are bringing down the broader market.

When stocks decline it typically helps interest rates improve.  Thus far mortgage rates are basically unchanged.

The Fed

The Federal Reserve Open Market Committee is scheduled to meet Tuesday-Wednesday with a monetary policy statement slated for Wednesday.  The markets fully expect the Fed to hike short-term interest rates by .25%.  This is already baked into the mortgage rate offerings you see today.

What can cause interest rates to move are the comments that accompany the rate hike announcement.  Will the Fed move more aggressively to hike rates in lieu of recent fiscal stimulus? Or given that recent inflation and wage growth data has been tepid will they stay the course with a “gradual” approach?

Don’t be alarmed when you hear Wednesday afternoon that the Fed is hiking rates by +.25%.  It does not necessarily mean that mortgage rates will follow suit.

The rest of the week

Aside from the highly anticipated Fed meeting I will be watching for the FHFA home price index report due out on Thursday and durable goods along with new home sales on Friday.

From a technical standpoint the yield on the US 10-year treasury note remains below 2.91%.  As long as this is the case rates should remain near current levels.

Current Outlook: floating

Home Loan Rates stable….for now

With today being the first Monday after daylight savings I think we can all agree this is the “Mondayest” Monday of the year.

Mortgage rates stable?

Mortgage rates fared ‘OK’ last week.  For the most part home loan rates were unchanged despite US stock indexes moving higher.  Normally interest rates worsen when stocks do well.

Don’t look now but mortgage rates have traded within a .125% range since mid-February.

Jobs report

Last Friday’s all-important jobs report showed much stronger employment growth than was expected.  However, wage growth actually slowed modestly which is probably why mortgage rates didn’t move higher on the news.  Higher wages can lead to inflation which is the nemesis of mortgage rates.

Rates getting squeezed

The technical outlook for interest rates has me concerned that we may experience a “breakout”.  The yield on the US 10-year treasury note is trading in a tight range between technical support and resistance.  When this happens we sometimes see yields sharply bounce outside of the compressed range.

The week ahead

This week’s economic calendar features a variety of reports that can drive interest rates. Later today the US Treasury will auction off $21 billion in US 10-year treasury notes.  If demand weakens for this asset it would likely pressure home loan rates higher.

On Tuesday we’ll get the latest reading of the Consumer Price Index, on Wednesday Retail Sales, and on Thursday the Producer Price Index.

The safe play is to lock and avoid any possible breakout.

Current Outlook: locking bias

Mortgage pre-qualification vs pre-approval

Video Transcript:

Hi, Evan Swanson here to talk to you today about the difference between a mortgage loan pre-qualification, and a mortgage loan pre-approval. The two differ based on the source of information used, and their ability to help you make an offer to buy a home.

Let’s start with source of information.

A mortgage loan pre-qualification is typically based on an initial conversation, and through that conversation we’ve collected information that’s been shared verbally about the person’s credit, their obligations, income, and money used for down payment. Through that conversation, we can deem that when it comes time for them to take out a loan, that that borrower should be able to qualify for a mortgage.

A mortgage loan pre-approval uses a source of information that is much more thorough, and therefore much more reliable. A mortgage loan pre-approval would be us collecting that information, putting it on a standardized loan application, collecting a credit report, and hopefully even collecting things like pay stubs, and W2’s to verify income, collecting assets to verify money used for down payment.

The mortgage loan pre-approval is much more thorough, and is the same process used by underwriters to actually approve loans.

Therefore, a mortgage loan pre-approval is much more reliable, and therefore a mortgage loan pre-approval is often required in order for a person to make an offer on a home, and have their offer taken seriously by a seller.

If you have questions about your ability to pre-qualify, or pre-approve, or what’s right at this time, we’d love to be a resource. Contact our office today, and set up an initial phone call. Thank you.


Mortgage rates will react to tariff sentiment

Congratulations to “The Shape of Water” for winning big at the Academy Awards last night.  I haven’t seen the movie but isn’t the shape of water simply the shape of its container?

Mortgage rates

Mortgage rates oscillated last week but are mostly unchanged from last Monday.  Fortunately the yield on the US 10-year treasury note remains below 2.91% which remains a critical technical level and one we’ll continue to monitor.

Tariffs and inflation

Last week President Trump announced proposed tariffs which would protect US steel manufacturers.  Higher prices for steel will likely pressure inflation higher and as we know inflation is the primary driver of mortgage rates.

As sentiment shifts around this issue I expect interest rates to react.  If it looks more likely that tariffs will be imposed mortgage rates will worsen and vice versa.

Jobs, Jobs, Jobs (and inflation)

This Friday we’ll get the all-important jobs report from the Bureau of Labor Statistics.  The markets are expecting +200,000 new jobs but lately interest rates have reacted more to the average hourly earnings number than to jobs.  Since the labor market is tight economists are watching wages to determine if companies will have to pay more in labor costs which can lead to wage-based inflation.

The remainder of the economic calendar is fairly light.

As long as the US 10-year treasury notes remains at or below 2.91% I will continue to float.

Current Outlook: cautiously floating

Eliminating mortgage insurance from a conventional loan


Video Transcript:

Hey there, Evan Swanson here to talk to you today about the elimination of mortgage insurance premiums from a conventional conforming loan.

There seems to be a lot of misinformation and confusion out there about when a consumer can get mortgage insurance premiums eliminated from their mortgage payment.

I like to describe it to customers from a best case and a worst-case perspective. Worst case is what’s written in the law under the Homeowners Protection Act, which is the federal statute, which governs this topic.

What that law says is that a lender can require mortgage insurance premiums to be paid so long as the remaining loan balance is scheduled to be above 78%-80% of the home’s original value. Original value is defined as the lessor of the purchase price or appraised value at the time the loan was taken out.

Worst-case scenario:

On a conventional conforming loan today, with 10% down at today’s interest rates it could take a consumer upwards of 6 years before they reach the point at which they have enough equity that they can have the mortgage insurance eliminated.

Best-case scenario:

Many loan servicers will allow consumers to get out of the mortgage insurance sooner than that, even though federal law doesn’t require them to. I’ve seen policies, which state that after a year, if the consumer has paid down the principle to below 80% of the original value, they can have the insurance removed.

I’ve seen others that show after two years, with the cost of an appraisal, if the consumer can demonstrate a 20% or more equity position that the mortgage insurance can be eliminated at that time. Typically, all these are going to require a clean payment history and some sort of documentation to the lender that the value on the property is what it is.

If you want to learn more about your options to eliminate mortgage insurance or if you want to ask questions, I’d love to be a resource for you and your family. Please, let me know how I can help. Have a great day.

A busy week for housing, for home loan rates 2.91% is key

One of my favorite days of the year took place on Saturday when Berkshire-Hathaway released its annual shareholder letter.  If you have never partaken in Warren Buffett’s simple, humorous, and sage advice I encourage you to dive in HERE.  Have kids?  This is all the financial education you need to give them.

Mortgage Rates

Mortgage rates held steady last week and even improved modestly for 30-year fixed rate amortizations.  I had written about the significance of the US 10-year treasury note yielding 2.91%.  Fortunately that technical level did hold and today it is trading at 2.86%.  As long as it trades below 2.91% I expect mortgage rates to hold steady (and possibly improve?).

Housing Data

This week’s economic calendar will tell us a lot about housing.  Earlier today new home sales were reported below economists’ expectations.  However, they are coming off record highs reported in November of 2017.

On Tuesday we’ll see the most current home price index reports from Case-Shiller and the FHFA.  On Wednesday the National Association of Realtors will release the latest pending home sale report.

The Fed

New Fed Chairman Jerome Powell will address lawmakers on Capitol Hill for the first time on Tuesday and Thursday.  Larger projected government spending deficits have increased speculation that inflation pressures will rise.  Inflation is the primary driver of home loan rates so we will be listening closely to his comments.

The Outlook

As long as the yield on the US 10-year treasury note remains at or below 2.91% I feel comfortable floating.  However, longer-term trends are still concerning so my advice is use caution this week.

Current Outlook: cautiously floating

What, when, why mortgage insurance?

Video Transcription:

Hi! Evan Swanson here to talk to you today about mortgage insurance. What is mortgage insurance, when is it required, and why do banks require it?

First, what is mortgage insurance? Mortgage insurance is insurance that homeowners pay for, and the bank is the beneficiary to the insurance coverage. It protects the bank against losses they would incur in the event of default or foreclosure on the mortgage they make.

When is mortgage insurance required? On conventional loans, mortgage companies typically require mortgage insurance whenever there’s less than 20% down. On FHA loans mortgage insurance is required regardless of down payment.

Why do banks require mortgage insurance? To answer that question we have to go back and look at what banks required prior to mortgage insurance. Banks required that everybody have 20% down and the idea was in the event of a foreclosure the bank would have incurred losses and that means they would have missed out on mortgage payments for somewhere between six and 18 months, meaning missed interest income.

If a person can’t afford to make their mortgage payments chances are they can’t afford to maintain the property so once they get the house back via the foreclosure process there’s deferred maintenance the bank has to pay for. The bank would have had to hire an attorney to execute the foreclosure process and then hire a realtor and pay a commission in order to sell the house. The banks require 20% down as their cushion to ensure that if they had to go through that foreclosure process they can still get their loan proceeds back.

Now there are a variety of ways to pay for mortgage insurance but without 20% down banks are going to require it.

If you’re curious about the different mortgage insurance options available to you and want to learn about them I’d love to be your resource for you. Please contact me today. Thank you.

While snow falls mortgage rates rise

I didn’t expect to see this much snow falling when I got up this morning.  Now I am just waiting for a tweet from the President accusing the National Weather Service of failing to predict this storm because they were too focused on the Russia investigation.

Do you know what isn’t falling?  Interest rates.  Mortgage rates rose another +.125% last week.  Might we finally get some reprieve and see rates stabilize or remove lower?  The answer to this question will largely depend on the US 10-year treasury note.

Mortgage rates tend to track changes in yield on the US 10-year treasury note.  For example since the beginning of the year the yield on the 10-year treasury note has increased by +.50% and mortgage rates have increased by about the same.

The US 10-year treasury note is currently trading very close to 2.91%.  It has traded very near this level since last Monday but has not managed to break through.  Assuming this technical layer of resistance can hold I would expect mortgage rates to remain at current levels.

If the yield on the US 10-year treasury note breaks above the 2.91% level  I expect mortgage rates to worsen by another .125%.

This week’s economic calendar features bond auctions from the US government.  As I have written about (HERE) we are beginning to see the supply of treasury auctions increase which will make it harder for mortgage rates to improve.

I will remain in a locking position.

Current Outlook: locking