What Is The Difference Between A Pre-Qualification & A Pre-Approval?

AdobeStock_103978598.jpegPortland has one of the hottest housing markets in the country. For a home-buyer the difference between being “pre-qualified” and “pre-approved” is key in having an offer accepted instead of ignored. Furthermore, there are even varying degrees of pre-approval that can impact a buyers chances of purchasing the home they want.

Pre-qualification simply means that a loan officer has interviewed a potential home-buyer and recorded information regarding their income, credit history, obligations, and assets. Based on the information shared in that conversation the loan officer believes the home-buyer will be able to obtain a home loan. However, none of the information regarding the home-buyers financial situation has been substantiated and therefore is not deemed reliable for a mortgage underwriter who is ultimately the one who makes the determination on whether a home loan application will be approved (or not).

When a home-buyer has been pre-approved, it means that the loan officer has received a completed home loan application (contact information, residency history, employment history, income, assets, other obligations, and other real estate owned). In addition, a pre-approval requires that a loan officer has also obtained a copy of the applicant’s credit report and determined that the person is in fact eligible to obtain a home loan.

However, here at Swanson Home Loans we recommend taking the pre-approval process one step further. In addition to the aforementioned loan application and credit report, we typically require an applicant submit supporting documentation. This allows us to review it and verify that the information supplied on the loan application does match the financial documentation that the underwriter will eventually review. Often times this involves having the applicant submit pay-stubs, W2 forms, copies of previous year’s federal tax returns, asset account statements, etc. In fact, we even have a member of our team who is a trained underwriter and reviews all this documentation prior to issuing a pre-approval letter.

These additional steps offer a couple benefits for the home-buyer. First, it allows us to issue a pre-approval letter that explicitly states that these additional measures have been taken which communicates to the seller that there is very little that can go wrong with the home loan process. In a competitive offer situation a home-buyer who has “crossed more hurdles” is closer to the finish line and will win out against another buyer who has only obtained pre-approval based on their application and credit report. The seller bares less risk without approach.

Second, by taking these steps before the home-buyer makes the offer it is one less thing they have to worry about when they enter into the process of completing their inspections and submitting their earnest money. In addition, it also positions us to possibly process the loan quicker and offer the seller a quicker closing schedule (which may be another compelling reason to accept the offer over others).

In summary, the steps a home-buyer takes to arrange their financing upfront is analogous to the old adage in the field of computer programming: “garbage in, garbage out”. When a home loan applicant does the least amount of work upfronanissat, the pre-qualification/ approval a lender delivers is inherently less reliable than an applicant who took additional steps upfront to submit a complete application.

Hopefully this piece is helpful for you and your search. Please let us know if we can be a further resource to you. Also, if you have any personal experience with this topic I invite you to comment!
Mortgage Rate Update May 23, 2016

Mortgage rates are unchanged from the latter half of last week.

The media is still focused on last week’s release of the Federal Reserve meeting minutes in which the committee indicated that a rate hike as early as June was in play.  I still don’t believe the Fed will hike rates in June.  According to CME Group there is a 26.3% probability currently priced into the market.  If the Fed does hike in June it could actually help mortgage rates because the move would be anti-inflationary.

The financial markets are still focused on the Fed's next move.
The financial markets are still focused on the Fed’s next move.

Fed chairwoman Janet Yellen is scheduled to speak this Friday and her comments will be closely scrutinized.

The rest of the economic calendar for this week is fairly light.  The highlights include the FHFA housing price index, new home sales, and pending home sales.  Recent housing data has been healthy and I expect this trend to continue.

The technical trading patterns for mortgage rates are not favorable but also not too concerning.  I will shift a neutral stance.

Current Outlook: neutral

Mortgage Rate Update May 19, 2016

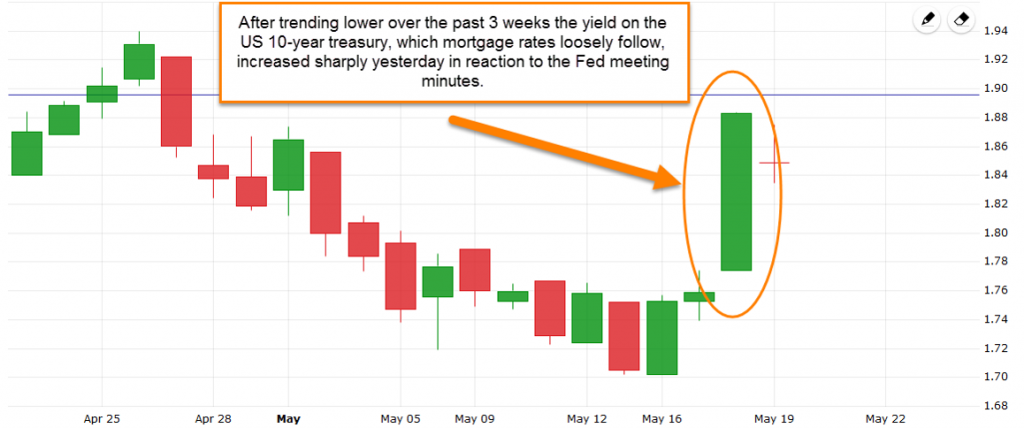
Mortgage rates worsened following yesterday’s release of the minutes from the most recent Fed meeting.  Have the markets overreacted?

The chart below shows the yield on the US 10-year treasury yield which increased sharply yesterday (mortgage rates followed suit).

05-19portland mortgage rates
Why this reaction?  The Fed meeting minutes signaled a possible Fed rate hike as soon as June (Fed meeting scheduled for June 14-15th).  However, in my view I do not believe this will happen.  The last Fed meeting took place in April before the most recent monthly jobs report was released.  As a reminder the most recent jobs report was weaker than expectations making it less likely that the Fed will hike rates.

I went into this week with a locking recommendation and that has proven to be the correct call.  Given that I believe the markets have overreacted to the release of the Fed meeting minutes I am going to shift back to a floating stance.

Current Outlook: floating

Mortgage Rate Update May 16, 2016

Mortgage rates remain near 3-year lows making it a great time to lock in a rate on a new home purchase or refinance.

Given that financial markets tend to operate in a cyclical manner I am currently recommending that customers lock their rate since they have trended lower over the past couple weeks (and therefore may “cycle” higher in the next couple weeks).

That said, many of the major banks have been revising their year end forecast for interest rates lower.  Last week Goldman Sachs lowered their expected yield on the US 10-year treasury yield following similar moves by Bank of America and Morgan Stanley.  Of course, if the banks knew for certain then there would be no need to revise so take this news for what it’s worth.

Recently, many of the major banks have peered into their crystal balls and revised their interest rate forecasts lower.

The economic calendar for this week is relatively short but there are some important releases.  Tomorrow the Labor Department will release the Consumer Price Index (CPI).  Inflation is the nemesis of mortgage rates and lately the year-over-year CPI figure has been creeping higher.  If this trend continues I wouldn’t be surprised to see rates tick higher.

On Wednesday the minutes from the most recent Fed meeting will be released.  Any additional information on the Fed plans certainly have the ability to move the markets.

I am going to recommend a locking bias simply because interest rates are extremely attractive levels.

Current Outlook: locking

Mortgage Rate Update May 9, 2016

Mortgage rates are modestly better to start the week.

In case you missed it Friday’s all-important jobs report was a miss.  The markets had been expecting 205,000 new jobs for the month of April and instead the report showed only 160,000.  This follows last month’s report which showed that only 156,000 new jobs were created during March.

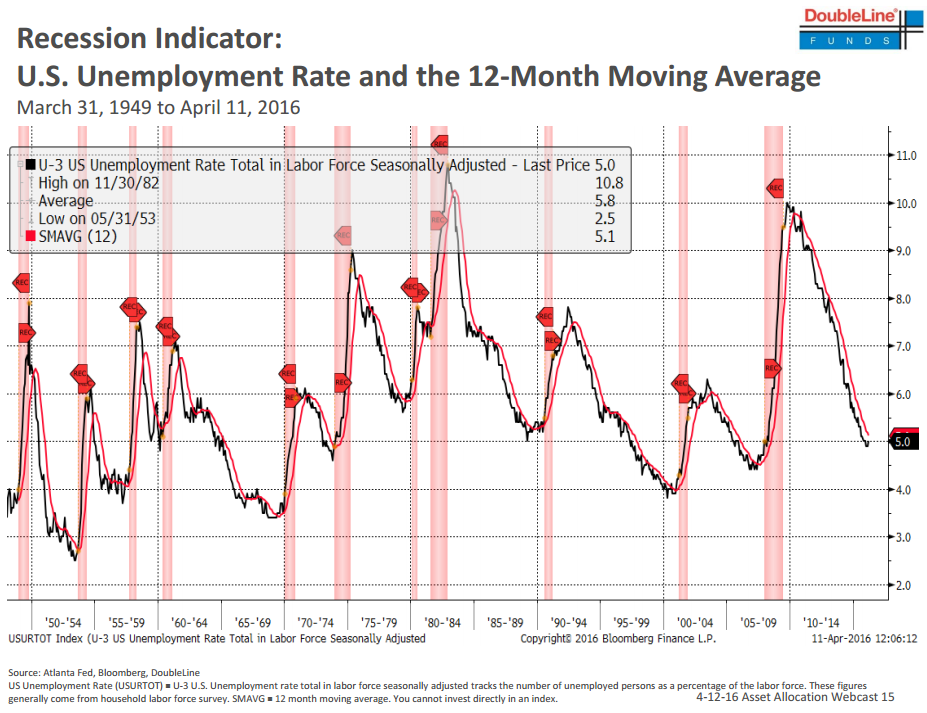
Despite the smaller than expected gains the US unemployment rate remained low at 5.0%.  With unemployment at such a low level it’s hard to imagine that an economic slowdown is on the horizon.  However, take a peek at the chart below:

Unemployment Rate Before Resssion5-9-2016-Portland-or-mortgage-rates

This demonstrates that going back to 1950 every recession starts with the unemployment rate reaching a multi-year low just before the economy begins to contract (recessions marked by pink highlights).  We don’t know if/ when a recession will come about nor how severe it will be.  It is interesting to note that US mortgage rates tend to dip during recessionary periods.

The economic calendar is relatively light this week.  I will shift to a floating position.

Current Outlook: floating

Mortgage Rate Update May 5, 2016

Mortgage rates are essentially unchanged from the beginning of the week.

The economic highlight of the week arrives tomorrow when the Bureau of Labor Statistics releases the monthly employment report (click HERE to learn how the report impacts mortgage rates) for April.  Current expectations are that 205,000 new jobs will be announced.

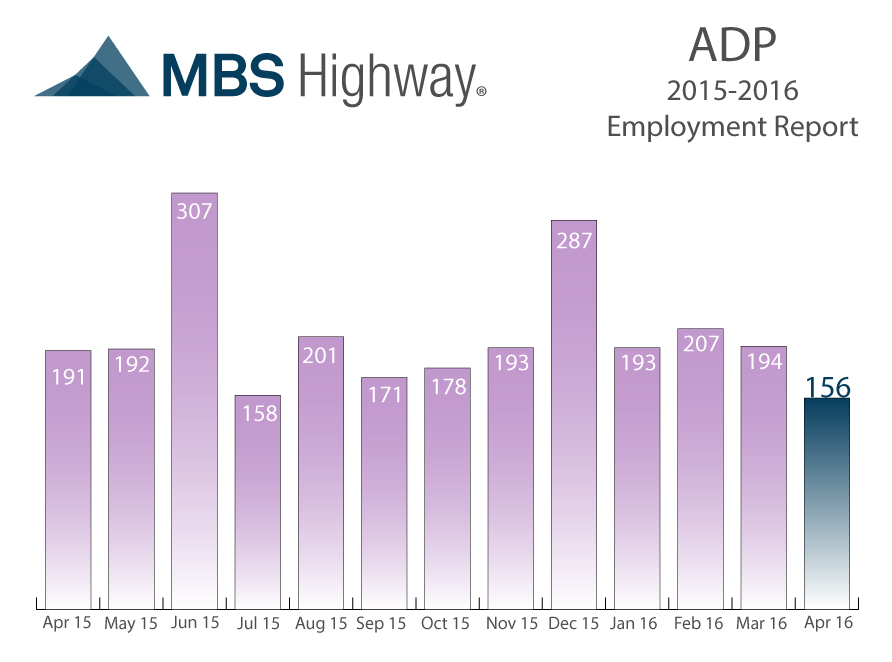
On Wednesday, private payroll company ADP released its version of the report which showed that only 156,000 new jobs were created last month.  This would suggest that tomorrow’s report may come in lower than expectations which would bode well for mortgage rates.

Portland mortgage rates ADP Employment Report5-4-2016


However, if you’ll remember back two weeks ago (see HERE) the weekly jobless claims numbers have been coming in at multi-decade lows.  This would leave us to believe that tomorrow’s report may be better than expectations.

As is the case every month this report is very hard to predict.  Given the current technical trading signals and the fact that mortgage rates are better this week than they were last week I am going to recommend locking in today.

Current Outlook: locking

Mortgage Rate Update May 2, 2016

Mortgage rates are unchanged from the latter half of last week.

Long-term interest rates, including mortgage rates, are inversely correlated to inflation.  This is because inflation essentially chips away at the return earned by lenders.  Inflationary pressure has been meek over the past few years as wages have been stagnant and commodity prices, including oil, have been low.  Is that beginning to change?

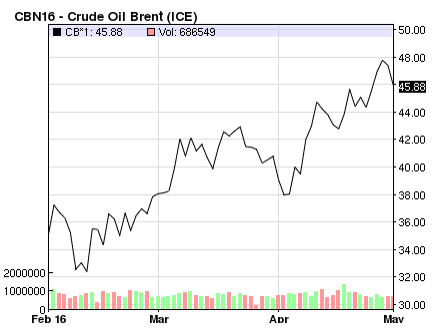
Strong gains in oil prices and a healthy labor market could lead to higher mortgage rates down the road.

Oil prices have risen ~70% since the beginning of the year and as we know the labor market has been producing jobs at a healthy clip which should eventually create wage pressure that can lead to inflation.  We will learn more about wages when the all-important jobs report is released on Friday.  Recent weekly jobless claim releases suggest that this Friday’s report should be strong.  If the current trend continues we’ll need to be cautious about inflationary pressure and therefore mortgage rates.

In the near term the technical trading signals in the interest rate markets look favorable.  I am going to start the week with a floating bias but I anticipate shifting to a locking stance on Thursday before Friday’s jobs report is released.

Current Outlook: floating

Mortgage Rate Update April 28, 2016

Although mortgage note rates are unchanged today the pricing is improved from Monday so in fact conditions are better.  Applicants should be able to lock today with slightly lower closing costs compared to earlier in the week.

Pricing for mortgage rates improved following the release of yesterday’s monetary policy statement from the Federal Reserve.  In effect, the committee maintained the language from the March meeting in which they held silent on when they plan to hike short-term interest rates.  As you’ll remember at the beginning of the year the markets had expected four .25% rate hikes during 2016.  Thus far there have not been any following the December 2015 hike and the markets think the Fed will remain on hold until Q4.

In other Central Bank news the Bank of Japan also held steady on their monetary policy today.  The markets had been expecting further monetary stimulus which could have helped US interest rates improve due to the fact that the US dollar would likely have strengthened against the yen.

The Central Banks in the US and Japan keep investors guessing.

In economic news, the Commerce Department reported that the US economy only grew by a .5% annualized rate during the 1st quarter of 2016.  This is slower growth than analysts had expected.  Bad news for the economy tends to be good news for mortgage rates.

Despite the slower than anticipated growth inflationary pressure appears to be picking up which is bad news for mortgage rates.  The Personal Consumption Expenditure price index, the Fed’s favorite gauge for inflation, was shown to have increased by 2.1% year-over-year.  This is up from 1.3% last quarter.  Should inflationary pressures persist the Fed will be forced to hike short-term interest rates even if they are not confident in the economic recovery.

Although momentum is back on our side the technical outlook for further improvements does not look favorable so I will maintain a locking bias.

Current Outlook: locking bias

Mortgage Rate Update April 25, 2016

Mortgage rates are unchanged from the second half of last week.  As I wrote about last Thursday mortgage rates increased by ~.125% over the course of last week.

This week’s economic calendar is jam packed with significant releases that could impact mortgage rates.

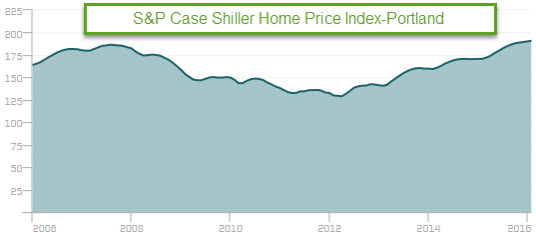
On Tuesday the latest version of the S&P Case-Shiller home price index is due out.  Portland has led the nation in year-over-year home price appreciation the past couple months and it will be interesting to see if we maintain the top spot.

04-25spcase

The Fed will conduct its regularly scheduled two-day monetary policy meeting Tuesday-Wednesday.  It is not expected that the Fed will raise short-term rates at this meeting but their comments regarding timing for future rate hikes would be an important market mover.  As a reminder the Fed does not directly control mortgage rates.

Later in the week we gets readings on personal consumption expenditures (inflation), personal spending, and consumer sentiment.

From a technical perspective as long as the US 10-year treasury yield is at or below 1.90% we can float in the hopes that it moves lower.  If it moves decisively above this level we need to lock in.

Current Outlook: cautiously floating

Mortgage Rate Update April 21, 2016

Mortgage rates have worsened slightly from the beginning of the week alongside the yield on the US 10-year treasury note.  On Monday the yield on the US 10-year treasury note was 1.77% and currently it is 1.88% (+.11%).

The culprit?  Positive signs for the labor are pressuring rates higher.

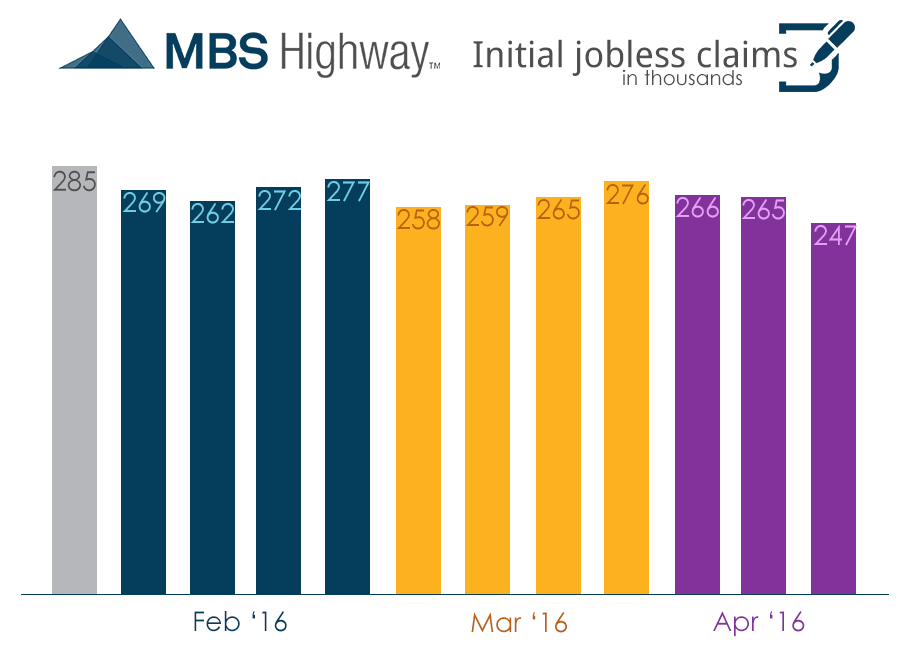
Each Thursday the Labor Department reports on the number of Americans who file for initial jobless claims.  The weekly indicator is a barometer for the health of the jobs market.  This week’s report showed that the number of Americans filing for jobless claims hit a 42-year low.  This week’s results will be factored into the next all-important jobs report scheduled for release on May 6th.  Good news for the labor market is often bad news for mortgage rates.

Initial Jobless Claims4-21-2016

From a technical perspective mortgage backed bonds look vulnerable to further price declines that would pressure rates higher.  The US 10-year treasury yield does have resistance that should help cap any additional moves higher.

Given that rates remain very attractive in historical terms I am going to recommend locking.

Current Outlook: locking