Mortgage Rate Update December 14, 2015

Mortgage rates are more or less unchanged from last week.

The big economic news story of the week is actually no news at all.  The Fed will meet tomorrow and Wednesday and make a monetary policy statement at the conclusion of the meeting.  There is a very high probability that the Fed will raise short-term interest rates by .25% on Wednesday.  This will not be a surprise as the markets are expecting it.

This week's headlines will focus on the Fed but the markets are already anticipating their next move.
This week’s headlines will focus on the Fed but the markets are already anticipating their next move.

Looking at this decision in a broad context it makes perfect sense.  During the last recession the US economy lost 8.7 million jobs.  We’ve since added 13 million jobs.  Although inflation and wages have only accelerated modestly over this time period they are starting to increase at a more aggressive clip.

Speaking of inflation, tomorrow we’ll get the latest reading on the Consumer Price Index (CPI) which is expected to reach 2.0% on the core reading for the first time in 19 months.  The rest of the economic calendar is relatively light.

From a technical perspective interest rates are trading between support and resistance.  For now we can begin the week by floating.

Current Outlook: floating
Mortgage Rate Update December 7, 2015

Housekeeping note: ‘Rate update’ will be on vacation (and hopefully on a golf course) this Thursday.  You can expect it to return one week from today.

Mortgage rates are unchanged from last Thursday.

We are now only 9 days from the Fed’s next announcement regarding US monetary policy.  The financial markets have priced an ~80% probability that the Fed will hike short-term interest rates at this next meeting.

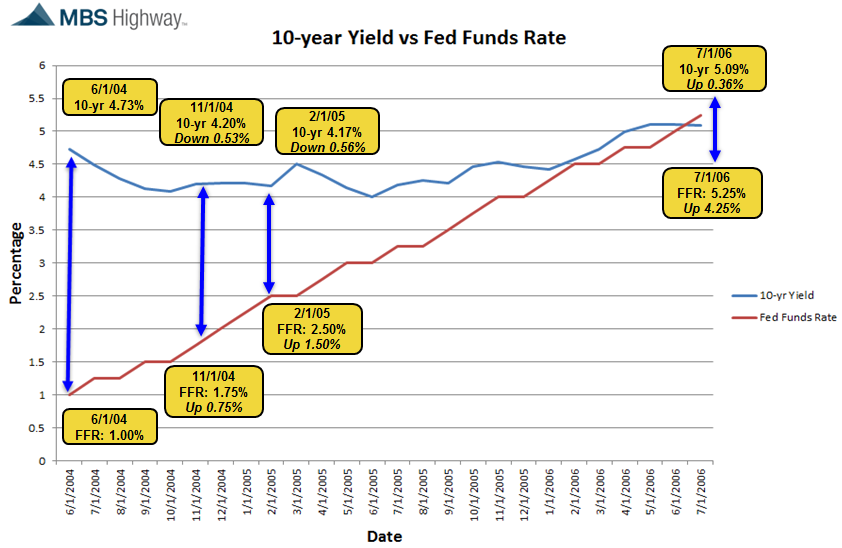
As I have stated numerous times on this blog a Fed rate hike does not necessarily mean that mortgage rates will immediately increase.  My friends over at mbshighway.com put together a great graph showing how mortgage rates reacted to the last tightening cycle which took place from June 2004 until July of 2006.

10-year Yield vs Fed Funds Rate12-7-2015

As you can see mortgage rates actually initially declined and then held mostly stable over the duration of this period.  How is this possible?  When the Fed raises short-term interest rates their objective is to curb inflationary pressure in our economy.  Inflation is the nemesis of mortgage rates.  Therefore, as the Fed hikes rates they concurrently curb inflationary expectations which is positive for long-term interest rates, including mortgages.

The economic calendar is relatively light this week.  We can start the week by floating.

Current Outlook: floating
Mortgage Rate Update November 30, 2015

Mortgage rates are slightly improved from last week.

Mortgage rates are benefiting from the projected divergence in monetary policy between the US and Europe.  Here in the US the Fed is likely to raise the Federal Funds rate at their next meeting scheduled for mid-December.  Meanwhile, speculation across the Atlantic is that the European Central Bank will move to further loosen monetary policy as soon as this Thursday.

When central banks loosen monetary policy, as Europe is expected to do, it effectively adds to the money supply and devalues the currency.  Conversely, when central banks tighten monetary policy, as the US is expected to do, it reduces the money supply and adds relative value to the currency.  Therefore, we are seeing investment capital flow into the US in anticipation of these moves and that is driving yields down slightly.

The US and Europe are taking divergent paths with regard to monetary policy.

In housing news, the National Association of Realtors reported that pending home sales rose by less than expected in October.  That said, the headline number is somewhat misleading because they also revised September’s previously released number up and without that adjustment the increase in pending sales would have been in line with expectations.

This week’s economic calendar is packed with significant data points.  The most attention will be focused on this Friday’s all-important jobs report.  Market expectations are for ~185,000 new jobs created last month and a number in line or better than expectations would cement expectations for a Fed rate hike in mid-December.  A severe miss in the new jobs number would definitely cause uncertainty in the financial markets.

Current Outlook: locking bias

Mortgage Rate Update November 23, 2015

Mortgage rates are unchanged from last week.

Let’s start off the week with some housing news.  The National Association of Realtors released its existing home sales for October.  The headline number of existing home sales fell from September but remains ~4% above October 2014.  Within the report there are some interesting details.

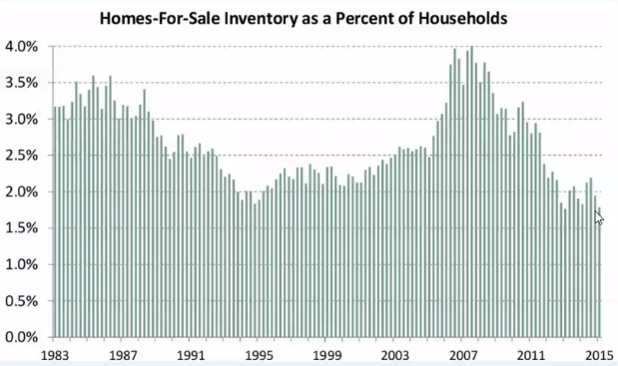
The inventory level for homes remains tight.  As a percentage of US households only 1.75% of the housing stock is currently available for sale.  This is well below the historic average of ~2.6%.  A tight supply is one main reason why prices continue to rise.  Speaking of prices rising, the median home price in the Western Region increased by 8% from a year ago.

Source: mbshighway.com

First time homebuyers accounted for 31% of all purchases, up from 29% in September.  Conversely, the number of distressed sales (foreclosure or short sale) declined and currently are 9% below October 2014.

The remainder of this compact work week is jammed with significant economic data.  Tomorrow we’ll get the second estimate for third quarter GDP and the latest S&P Case Shiller Home Price Index report.  On Wednesday we’ll get personal income, personal consumption expenditure price index, the FHFA home price index, durable goods, and new home sales.  Needless to say we could see volatility for the remainder of the week especially since many trading desks will likely be vacant on Wednesday.

From a technical perspective mortgage rates are trading near important technical levels.  We will want to keep an eye on the US 10-year treasury yield this week.  It is currently trading at 2.27%.  Should it pierce above 2.33% I will shift to a locking position.

Current Outlook: floating as long as the US 10-year treasury is at or below 2.33%.

Mortgage Rate Update November 19, 2015

Mortgage rates are essentially unchanged from the beginning of the week.

Yesterday the minutes from the last Federal Reserve monetary policy meeting showed that the Fed does intend on raising short-term rates at the December 15th-16th meeting as the markets have been expecting.  That said, the Fed did leave themselves an out by stating that a very weak jobs report or an unexpected geopolitical event could alter the plan.

The markets have essentially already priced in a Fed rate hike in December so in and of itself that even should not change interest rates.  That said, their comments from now until then and other economic releases could influence rates.

There are no more economic data points set for release this week.  Therefore, we’d expect mortgage rates to react to technical trading patterns.  At this point mortgage-backed bonds and the yield on the US 10-year treasury note are trading in between a wide range and momentum appears to be favorable.  I will recommend floating into next week but given that trading desks on Wall Street will likely be vacated after Monday (holiday week) we could see some volatility.

Current Outlook: locking bias

Mortgage Rate Update November 16, 2015

Mortgage rates effectively moved sideways last week.  We have a very modest improvement this morning which may be short lived.

There are two events on the economic calendar that have me concerned this week.  Tomorrow we get the Consumer Price Index (CPI) from the Labor Department.  Consensus estimate for Core CPI (strips out volatile food + energy prices) is that year-over-year retail inflation will hit 2.00%.  The Core CPI has been at or below 2.00% since the summer of 2012.  Inflation is the primary driver of long-term interest rates, including mortgages.

Core CPI has been at or below 2% for over 2 years. (Source: Bureau of Labor Statistics)

Second, the minutes from the last Fed monetary policy meeting are scheduled to be released on Wednesday.  Recent releases have not been kind to mortgage rates so I think we have to assume this one could be trouble as well.

A look at the financial markets suggests that most investors think long-term interest rates will increase in the next year but not in a rapid fashion.  According to the Wall Street Journal investors have accumulated $16.4 billion in net short positions for the US 10-year treasury note, the highest level since May (these investments pay-off when rates rise).  In addition, US bond mutual funds saw $2.13 billion net cash outflow the largest withdrawal since May.

Given the aforementioned events I am going to recommend a locking stance.

Current Outlook: locking bias

Mortgage Rate Update November 12, 2015

Mortgage rates are unchanged from the beginning of this week.

As I wrote on Monday I don’t believe it is any coincidence that markets presently believe the Fed is likely to raise short-term interest rates by .25% at the Dec. 15th-16th meeting and mortgage rates have increased by .25% over the past couple weeks.  Speaking of the Fed Janet Yellen is scheduled to speak later today and her comments can always impact the direction of rates.

The question I have is will rates continue to trend higher?  At the beginning of this week momentum in the interest rate markets led me to believe that it could very well be the case.  However, interest rates stabilized on Tuesday and the bond market was closed on Wednesday in recognition of Veteran’s Day.

Now that mortgage rates have increased by .25% in the past couple weeks will they continue to trend higher?  or stabilize?
Now that mortgage rates have increased by .25% in the past couple weeks will they continue to trend higher? or stabilize?

At this point I don’t see a catalyst in the near-term that would cause mortgage rates to improve.  Sentiment has changed in the interest rate markets and is not favorable for rates moving lower at least in the near-term.

From a technical perspective mortgage rates would need to increase by another .125% to match 2015 highs. Whether or not this happens in the near-term may have to do with the yield on the US 10-year treasury note.  It is currently trading at an important technical layer @ 2.33%. A close above this level would  be a bad sign.

For now, I think the safe play is to take the long-term historical perspective and recognize on a historical scale rates below 4.5% are damn good.  I will maintain a locking bias but won;t be surprised if rates hang around these levels for a little while.

Current Outlook: locking bias

Mortgage Rate Update November 9, 2015

Pricing for mortgage rates continues to worsen.

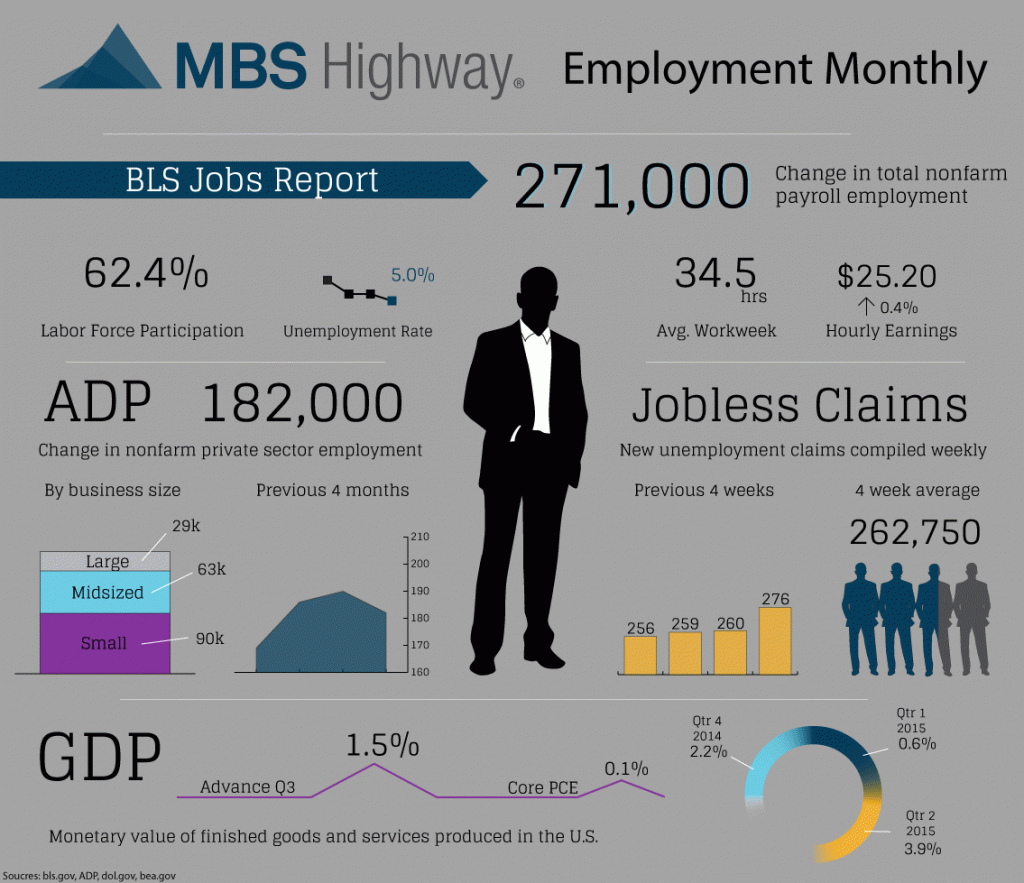
In case you missed it Friday’s all-important jobs report came in stronger than expected.  The release showed that US employers added 271,000 new jobs during the month of October.  It also showed that average hourly earnings increased 2.5% from a year earlier.  As I have written about multiple times on ‘rate update’ wage growth has been all but absent during this economic expansion which is one reason why inflation has remained below the Fed’s target of 2%.  If wages continue to grow one would assume this would eventually create inflationary pressure which is bad for mortgage rates.

Employment-Monthly-11-9-2015

With a stronger than expected jobs report in hand the markets now are pricing in a 70% probability that the Fed will hike at the next monetary policy meeting slated for Dec. 15th-16th.

Unfortunately many consumers are not aware that the Fed does not directly control mortgage rates and therefore may think they have until December 16th to lock in “today’s low rates”.  However, longer term yields have already reacted.  Back on October 27th the yield on the US 10-year treasury note was ~2.05%.  As of this morning it is yielding ~2.35% (+.3%).  Mortgage rates have increased by ~.25% over this same time period.

Looking ahead for the remainder of the week the financial markets will be closed this Wednesday in honor of Veteran’s Day.  On Friday we’ll get a reading on the Producer Price Index and Retail Sales.

It’s been a difficult couple weeks for mortgage rates and momentum is still working against us.  I will maintain a locking bias.

Current Outlook: locking

Mortgage Rate Update November 5, 2015

Pricing for mortgage rates continue to worsen as the markets increasingly believe the Fed will raise short-term interest rates at the December meeting.  According to CME Group the markets currently believe there is a 56% chance the Fed will hike (last week it was 50%).

With all the focus on the Fed over the past few weeks the 3rd quarter earnings season has been largely ignored.  Despite the fact that yields have been inching higher the news out of the stock market is not great.  According to Bloomberg, with roughly 75% of the S&P 500 already reporting overall profits are down 3.1% which represents the biggest quarterly drop since the third quarter of 2009.  Bad news for stocks tends to be good news for mortgage rates.

close up of chalkboard with finance business graph
Stocks in the S&P 500 have seen profits decline but mortgage rates are trending higher.

Unfortunately, I don’t expect mortgage rates to react to the stock market anytime soon.  Tomorrow we get the all-important jobs report for October.  The last two releases have shown modest job growth (Aug. +136,000, Sept. +142,000).  Expectations are currently set at +181,000.  Given that recent jobless claims numbers have been relatively strong I wouldn’t be surprised if job growth exceed expectations which would not be good for mortgage rates.

Furthermore, the US unemployment rate was reported at 5.1% for September and is expected to come down to 5.0% in tomorrow’s report.  Should the unemployment rate dip even further to 4.9% then a December rate hike would likely become a certainty.

With momentum heading in the wrong direction technical trading patterns are also not on our side.  I am going to recommend locking in today.

Current Outlook: locking

Mortgage Rate Update November 2, 2015

Mortgage rates are more or less unchanged from last Thursday’s ‘rate update’.  As I wrote then mortgage rates have risen by ~.125% since the Fed’s monetary policy statement delivered on Wednesday of last week.  Investors now assign a 50% chance that the Fed will increase short-term interest rates at the December meeting.

11-2-CME

It’s hard to believe it’s November 2nd!  A new month means a new all-important jobs report which is slated for Friday.  Analysts will be watching this one closely as it may influence whether or not the Fed acts to hike rates in December.  I will lay out my strategy headed into this report in Thursday’s ‘rate update’.

From now until then there is a scattering of other economic data points but I expect mortgage rates to remain relatively flat until the end of the week.

From a technical perspective interest rates appear vulnerable.  The US 10-year treasury yield is trading right at an important technical level.  If yields close above this level it would be a bad sign for mortgage rates and if they can retreat below it would be a positive sign.

Current Outlook: neutral