Mortgage Rate Update March 3, 2016

Mortgage rates are unchanged for the week.  That may all change tomorrow with the release of the all-important jobs report.

If you remember back to last month the jobs report missed expectations coming in at only 158,000 new jobs created.  This month analysts expect the report to show 190,000 new jobs created.  If the actual figure comes in higher than expected mortgage rates are likely to worsen and vice versa.

It’s always difficult to predict the monthly jobs report but based on what I am seeing I think there is more risk in floating than there is in locking.  Why?

First, from a technical perspective momentum is working against us.  See the chart below.
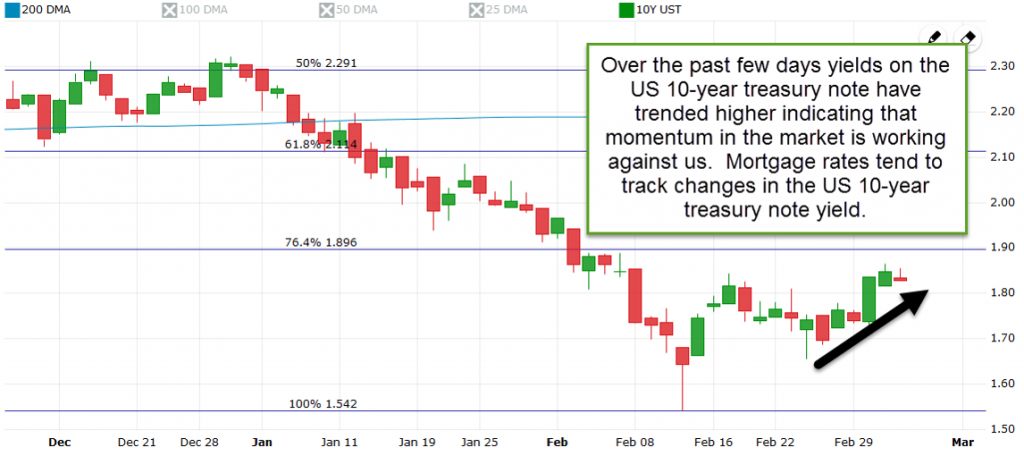
03-03-US 10yr Mortgage Rates Portland Oregon

Second, recent domestic economic data has been relatively healthy.  Private Payroll company APD released its version of the monthly jobs report yesterday and it showed that 214,000 new jobs were created last month.  In a separate release, the Fed released a report which showed that consumer spending rose in much of the nation during the first part of the year.

Lastly, given that last month’s report was released well below expectations I believe that there is a greater likelihood that it will be subject to a revision higher which would put upward pressure on mortgage rates.

Current Outlook: locking
Mortgage Rate Update February 29, 2016

Mortgage rates are similar or slightly worse compared to Thursday.

Interest rates here in the US continue to be influenced by international storylines.  China’s central bank announced today that it will cut reserve requirements on Chinese Banks in an effort to boost lending in their economy.  Asian stock markets reacted negatively to the news which provides support for the “flight-to-safety” trade that helps US interest rates remain low.

In a separate release inflation figures out of Europe were reported very low earlier today.  The report makes it more likely that the European Central Bank will expand its quantitative easing measures when they meet again in March.  That expectation will encourage demand for US dollar denominated assets and make it harder for US interest rates to increase.

In domestic housing news the National Association of Realtors released its monthly pending home sales report.  It showed the numbers of homes pending in the US declined last month but is still 1.4% higher than a year ago.  Harsh weather on the east coast and lack of supply were credited with the decline.

Harsh winter weather on the east coast is being blamed for lower pending home sales in January.

Looking ahead it is jobs week and the rest of the economic calendar is busy.  From a technical perspective mortgage rates look safe so we’ll maintain a floating bias.

Current Outlook: floating bias

Mortgage Rate Update February 25, 2016

Mortgage rates are similar or slightly better compared to Monday.

China’s stock market plunged for the second time this year.  The Shanghai Composite Index fell by 6.4% today as investors showed concern for the state of the Chinese economy.  The volatility in China has redirected capital into the US debt markets which helps rates move lower (click HERE to learn how).

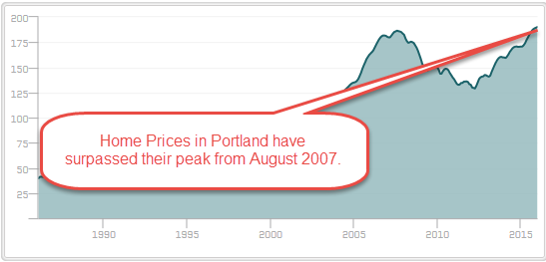
In case you missed it Portland led the country in year-over-year home price appreciation according to the latest Case-Shiller Home Price Index report that was released on Tuesday.  According to the report home prices rose by 11.4% from December 2014 to December 2015.  Some onlookers have begun to ask if a bubble is forming here in Portland.  Click HERE to see why we’re not there…..but not ruling it out in the future.

Case-Shiller Home Price Index- Portland, OR

In other housing data, the National Association of Realtors NAR released monthly data on existing home sales.  Nationally home sales increased to a 6 month high.  However, the number of home sales actually decreased in the West Region from December to January (still higher on a year-over-year basis).  A lack of supply was blamed.

NAR chief economist Lawrence Yun commented, “The spring buying season is right around the corner and current supply levels aren’t even close to what’s needed to accommodate the subsequent growth in housing demand.”  You can say that again.

From a technical perspective the outlook looks modestly positive.  I will shift to a floating bias.

Current Outlook: floating bias

Mortgage Rate Update February 22, 2016

Mortgage rates are unchanged from the latter half of last week.

Friday’s Consumer Price Index (CPI) report from the Bureau of Labor Statistics suggests that the Fed may have to get back on the path of hiking rates.  The report showed that the Core CPI, prices for consumer goods excluding food and energy, rose by 2.2% on a year-over-year basis.  This is the “hottest” figure since June 2012 and above the Fed’s target of 2.00%.  Inflation is the primary driver of long-term interest rates including for home loans.

Is inflation ahead?  If so, it would pressure mortgage rates higher.
Is inflation ahead? If so, it would pressure mortgage rates higher.

This Friday we’ll get the Personal Consumption Expenditure price index which is the Fed’s favorite gauge for inflation.  If that also comes in higher than expected then it would likely pressure mortgage rates up.

Looking at the rest of the economic calendar this week the Case Shiller Home Price index is due out tomorrow.  We’ll also get readings on consumer confidence and existing home sales.  On Wednesday the FHFA will release their home price figures and on Friday we’ll get the 2nd estimate for 4th quarter 2015 GDP.  I wouldn’t be surprised to see some volatility this week given the depth of data scheduled for release.

From a technical perspective mortgage rates are trading within a ~.125% range.  I don’t necessarily see a catalyst for rates to improve in the near-term but I also don’t see them increasing so I will shift to a neutral position.

Current Outlook: neutral

Mortgage Rate Update February 18, 2016

Mortgage rates are unchanged from Monday.  Mortgage rates remain slightly worse as compared to last Wednesday-Thursday.

US stocks started the day higher but have since stalled, which bodes well for interest rates.  Worries over slowing global growth have re-emerged which drives capital into perceived “safe-havens” including the US debt markets and drives our yields lower.

Is the US economy on the brink of an economic slowdown?  The Philadelphia Fed released its monthly barometer for manufacturing and it remained in negative territory which signals continued contraction for manufacturing.  Bad news for the economy tends to be good news for mortgage rates.

Continuous weakness in the manufacturing sector has some investors worried.

Tomorrow we’ll get the latest reading on the Consumer Price Index (CPI).  Inflationary pressure remains weak in our economy (exception: housing costs in Portland, OR) and we’ll see if that trend continues. If so, that fact coupled with fears over an economic slowdown will put the Fed on hold in hiking short-term interest rates.  The next Fed monetary policy meeting is scheduled for March 15th-16th and the markets think there is a 94% chance the Fed will not hike.

From a technical perspective there is reason to believe that mortgage rates can regain the .125% they lost late last week so I am going to recommend cautiously floating.

Current Outlook: floating

Mortgage Rate Update February 16, 2016

Mortgage rates have worsened since last Thursday’s ‘rate update’.

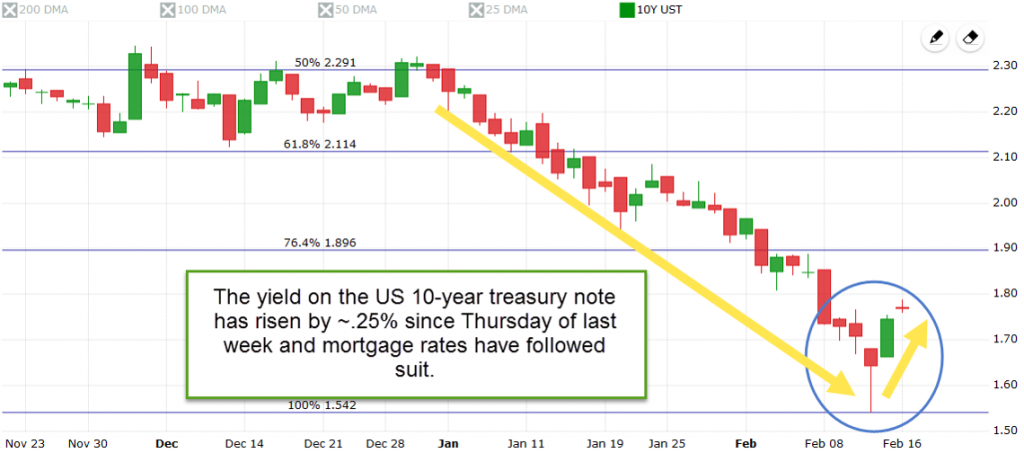
After touching multi-year lows on Thursday of last week the US 10-year treasury yield has bounced higher by nearly .25% and 30-year fixed rate mortgage terms have followed suit.

02-16-10yr

Why have rates risen so acutely?  Yields had been driven lower thanks to a “flight-to-safety” which had been underway since the beginning of the year.  Fears over China’s economy, Europe’s stability, and oil prices had driven investors into perceived “safe-havens” which is the primary reason why rates have been pushed to historically low levels.

Will this pattern continue?  At least in the immediate term it looks like sentiment has changed.  From a technical perspective we’ll be watching to see if rates drift further away from the recent trading range.  Or, do they get pulled back into the recent trading range?

Looking at the economic calendar for this holiday shortened week inflation gauges highlight the week.  On Wednesday we get the Producer Price Index and on Friday we get a peek at the Consumer Price Index.  It is my view that as long as inflationary pressure remains muted in our economy that mortgage rates will remain low.

Given that momentum has shifted I am going to recommend locking.

Current Outlook: locking

Mortgage Rate Update February 11, 2016

Mortgage rates continue to improve.  30-year fixed rates are now only .125% above the all-time low levels created in the fall of 2012.  It is a great time to review your loan and evaluate your options for refinancing.  There is a good chance that if you or someone you know has a fixed rate at 4.25% or higher, good credit, and at least 10% equity then we can refinance your note with little or no cost and reduce your payments or loan term.

Why are rates improving so dramatically?  First off, stock markets around the globe are down sharply today.  As I type the US Dow Jones Industrial Average is down 2.06%, the Japanese Nikkei 225 is off 2.31%, and in London the FTSE is down 2.39%.  Investors are shedding “riskier” assets and seeking safety which is driving yields lower.

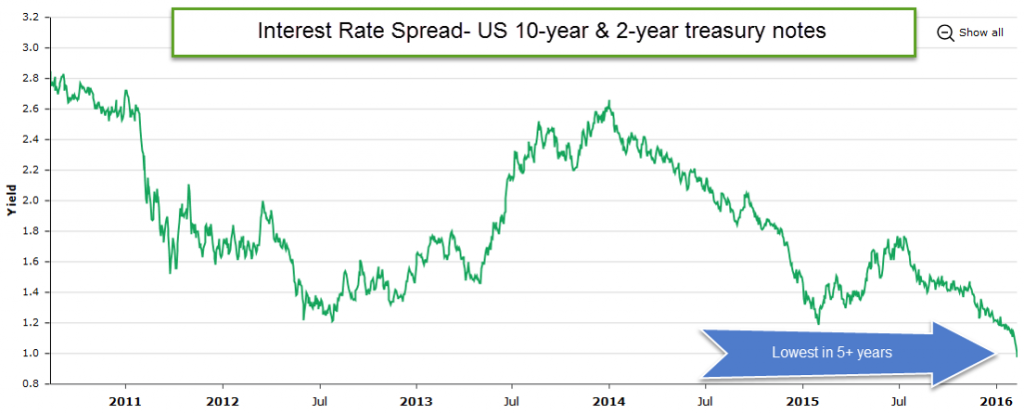
The yield on the US 10-year treasury note is down to ~1.60%.  The spread between the US 10-year & 2-year treasury note is at its lowest level in 5 years which is a negative sign for the economic outlook.

02-11-102yr
Another reason for the convergence in yields is that inflationary pressure remains weak in our economy.  In testimony yesterday Fed Chairwoman Janet Yellen highlighted the financial turbulence and acknowledged that it could prevent inflation from increasing this year.  In other words, additional Fed rate hikes are likely on hold until things settle down.

Current Outlook: floating

Mortgage Rate Update February 8, 2016

Mortgage rates remain at the best levels in the past 12 months.

Friday’s all-important jobs report was a miss.  The markets had been expecting +188,000 new jobs and the report showed only +158,000 jobs created during the month of January.  Furthermore, the Bureau of Labor Statistics revised lower its previously released figure for December.  Bad news for the economy is often good news for mortgage rates.

Speaking of bad news, the stock market is off to a rough start this week.  As I type the Dow Jones Industrial Average is off ~350 points (-2.18%).  Germany’s DAX index was off by ~3% today.  Market sentiment has turned sour on the global economy.

Global weakness continues to help US mortgage rates move lower.


Last week China released data showing their manufacturing sector declining at the fastest clip in 3 years.  In Europe there is growing concern over the stability of their financial sector because of their exposure to emerging markets (which generally rely on commodity prices to repay debts).

All in all fear and uncertainty are currently driving the markets and US interest rates tend to benefit when this holds true.  We will shift to floating until we see sentiment begin to change.

Current Outlook: floating

Mortgage Rate Update February 4, 2016

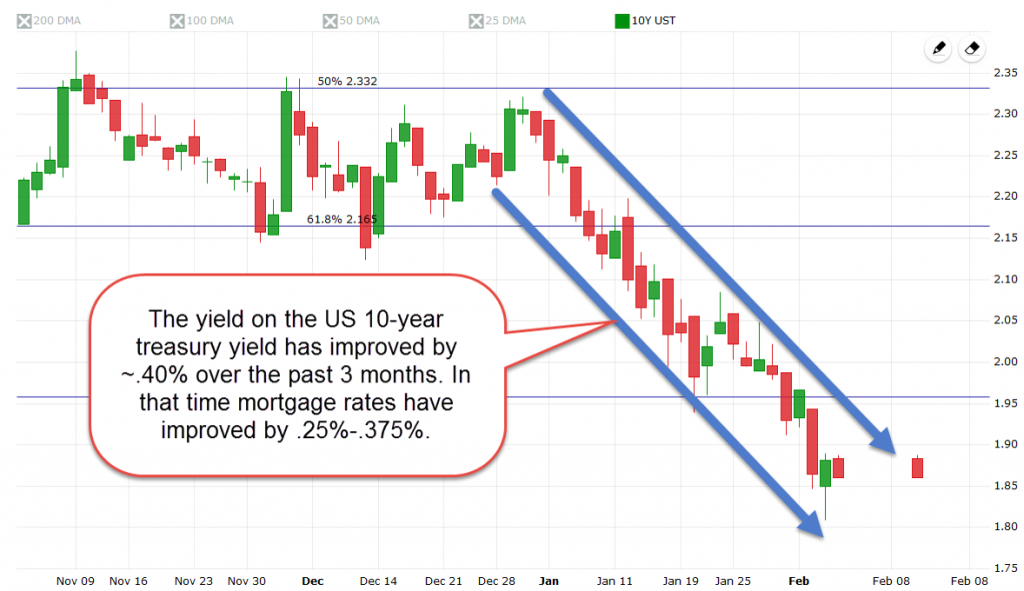
Rates are mainly unchanged from Monday.  Mortgage rates have improved by .25%-.375% over the past 3 months. The chart below demonstrates the correlation between changes in the US-10 year and mortgage rates.

02-04-10yr

Tomorrow we get the latest all-important monthly jobs report from the Bureau of Labor Statistics.  In case you’ve forgotten last month’s report showed that 292,000 new jobs were created but a deeper look into the report showed that many of those were seasonal.  As a result, despite the stronger than expected headline number mortgage rates did not increase you we would have expected.

The markets are currently expecting only 188,000 new jobs created during the month of January.  Given the lower bar it would seem more likely that the report could surprise to the upside which would hurt mortgage rates.  However, looking at the aforementioned chart we do have momentum on our side.

The next Fed meeting is scheduled for March 15th-16th so this jobs report will not have as much significance because there will be one more released on Friday, March 4th.

The monthly jobs report is always difficult to handicap.  The momentum in the marketplace is playing to our favor so I am inclined to float.  That said, we’ve had a great run in the past 90 days so the safe play is to lock in while we’re ahead.

Current Outlook: locking bias

Mortgage Rate Update February 1, 2016

Mortgage rates are slightly better as compared to last week.

Last Friday the Bank of Japan, which is the central bank, surprised the global markets by cutting short-term interest rates in that economy.  Their short-term interest rates are now negative which means commercial banks must now pay the Bank of Japan for the privilege of parking cash in their vaults.  The purpose is to encourage banks to lend money to businesses and consumers to increase economic activity in that country.

Last week the Bank of Japan surprised the global markets by cutting short-term rates into negative territory.

That announcement coupled with the possibility that the European Central Bank increasing stimulus efforts in March puts the United States Federal Reserve in an awkward position because they had intended on hiking short-term interest rates this year.

In domestic economic news, the personal spending report was released earlier today.  embedded inside this release is the Fed’s favorite gauge on inflation known as the Personal Consumption Expenditure Price Index (PCE).  The PCE showed that prices in the US economy increased by only 1.4% over the past 12 months which is well below the Fed’s target of 2.0%.  One thing to note about the PCE is that it does not include out of pocket costs for health care or the cost of housing (rent/ home prices).   Given that home prices and rents have risen so rapidly in the past 24 months I think we need to accept today’s report with a giant grain of salt.

Looking ahead and the remainder of the week the all-important jobs report will take center stage.  From a technical perspective mortgage rates have had a great run.  I am concerned that we will see a reversal of sentiment in the markets.  I am maintaining a locking bias.

Current Outlook: locking bias