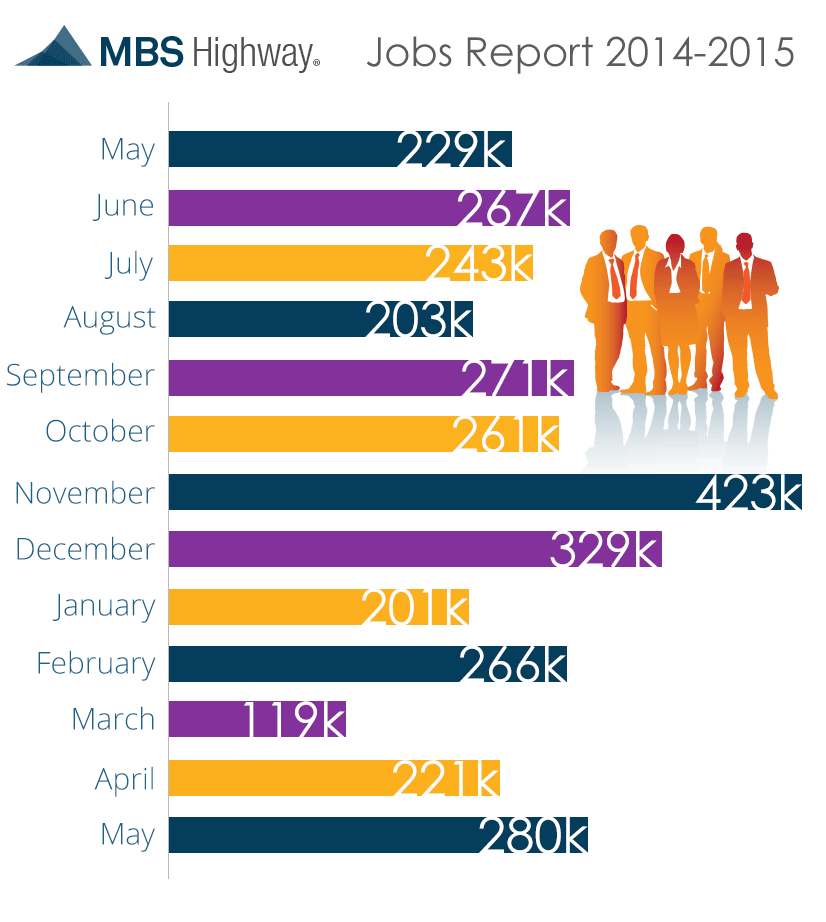Mortgage Rate Update June 29, 2015

Although mortgage note rates are unchanged from last Thursday pricing has improved so in fact the overall rate environment is better to start the week.

Greece is back in focus for the financial markets today.  Although Greece is not yet technically in “default” they are teetering on the edge.  Negotiations between Greece and its creditors have broken down just 24 hours before the ailing country is scheduled to make a 1.6€ billion payment.

Greece has implemented strict capital controls in order to keep its financial system from crashing.  The Greek stock market is closed, bank branches are closed, and ATM’s are open but Greek citizens are limited to withdrawing 60 euros per day (~$67).

Euros are a little more scarce in Greece today....and US mortgage rates are benefiting.
Euros are a little more scarce in Greece today….and US mortgage rates are benefiting.

The chaos in Greece has ignited a “flight-to-safety” in the financial markets.  As I explain HERE this is a good sign for US mortgage rates.

For the time being mortgage rates will likely respond to developments in the Greek saga.  However, it is a very busy compressed economic calendar this week (the financial markets are closed on Friday).

In housing news the National Association of Realtors reported that pending home sales hit a 9-year high last month.  Tomorrow S&P will release the latest reading on the Case-Shiller Home Price Index.

It’s jobs week so we’ll get the ADP, initial claims, and the all-important jobs report later in the week.  We will be keeping a close eye on wage growth in this Thursday’s jobs report as that is the missing piece of the inflation puzzle which will force the Fed’s hand in raising rates.

Current Outlook: floating
Mortgage Rate Update June 25, 2015

Mortgage rates are mostly unchanged from the beginning of the week.

Interest rates have been choppy this week.  On Monday it appeared that mortgage rates were headed higher on news that Greece was close to reaching a deal with their creditors.  However, news emerged yesterday that its creditors would not accept the proposal.  Therefore, rates improved.  And today rates appear headed higher on better than expected economic news.Inflation concept.

This morning’s read on inflation came from the Personal Consumption Expenditure price index (PCE).  It showed that on a year-over-year basis consumer prices rose by only 1.2% here in the US.  This is well below the Fed’s target of 2% and will make it hard for the Fed to raise rates.

What is interesting is the Consumer Price Index, a separate measure of inflation, is currently reporting a +1.8% year-over-year increase so the disconnect may make it hard for the Fed to really know what price pressures exist in the economy.

In a separate release weekly jobless claims were shown to remain near historic lows.  The employment picture in the US remains strong but inflation is tame.  Inflation will come and when it does it will pressure interest rates higher.

Current Outlook: locking

Mortgage Rate Update June 22, 2015

Mortgage rates are unchanged from last week but are trending in the wrong direction this morning.  Last week mortgage rates caught a break from their upward trend that had been established a few weeks ago.  The break was as a result of renewed fears over the Greek financial crisis.

Those fears are unwinding this morning as reports out of Europe suggest that Greece and its creditors may be close to a deal that would prevent a default.  This is a very fluid situation so sentiment can change in a heartbeat but for now it appears that mortgage rates may firm up due to reduced fear surrounding the Greek situation.

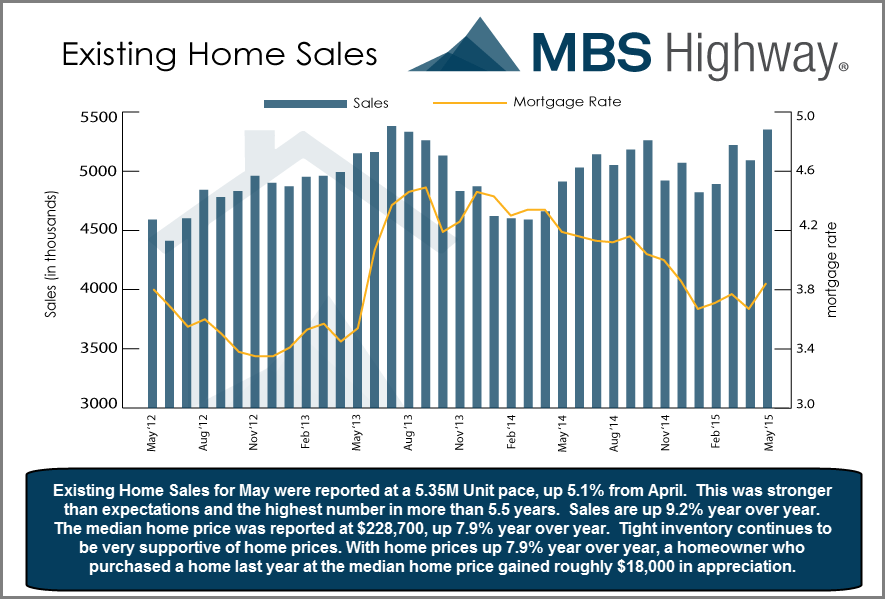
There was a great housing report from the National Association of Realtors (NAR) released earlier today.  The report showed that the number of existing home sales in the US increased by 9.2% from last year (+9.0% in the west).  The number of home sales has now increased for eight consecutive months.  In the west the median home price rose by 10.2% from last year.

existing-home-sales-6-22-15

Looking ahead, on Tuesday we’ll get figures on new homes sales, on Wednesday we’ll get a report on US Gross Domestic Product, and on Thursday we’ll get the Fed’s favorite gauge of inflation (Personal Consumption Expenditure price index).

Last thing, in case you missed it the Consumer Financial Protection Bureau announced a two month delay on the implementation of their new mortgage disclosure regime known as “TRID” (TILA-RESPA Integrated Disclosure).  The new disclosures were scheduled to begin with new loan applications started on August 1st and now it will be October 1st.

Current Outlook: locking

Mortgage Rate Update June 18, 2015

Mortgage rates are unchanged from Monday.

In case you missed the Fed’s statement following their monetary policy meeting yesterday they indicated that they would raise rates on a gradual basis.  This means that the market now thinks that Fed will increase interest rates on a slower pace than previously expected.  At first glance this may seem like good news….but in fact this is not favorable for mortgage rates.  Why?

It’s been a while so I will reiterate that inflation is the primary enemy of mortgage rates.  When a lender makes a loan and will be repaid in the future they have to take into account the projected purchasing power of that future repayment in setting a rate of interest to charge a borrower.

Rate hikes may be coming slower than we all thought....and that is not good for mortgage rates.
Rate hikes may be coming slower than we all thought….and that is not good for mortgage rates.

Since the great recession inflation has consistently been below the Fed’s target of 2% which is part of the reason why mortgage rates have remained near historically low levels.  In fact, the Consumer Price Index was reported today and it showed prices continuing to rise by less than 2% on a year-over-year basis.

However, the interest rate markets are forecasting that inflation will be picking up in the near future.  This is evident in mortgage rates increasing by .25%-.50% over the past month.

When the Fed increases short-term interest rates is helps to curb inflationary pressure.  Therefore, by the Fed taking a slower approach to raising rates than previously thought it is more likely that they could get behind the curve in fighting inflation.  This is why yesterday’s announcement was actually unhelpful to rates moving forward.

I am going to shift to a locking bias given this new information.

Current Outlook: locking

Mortgage Rate Update June 15, 2015

Mortgage rates are unchanged from last Monday.

The financial travails in Greece are back in the headlines this morning.  Over the weekend talks between Greece and its creditors broke down.  Greece is supposed to pay the International Monetary Fund a 1.6 billion euro payment by the end of June.  There is growing speculation that they will not meet that obligation which could throw Greece’s financial system into chaos.  The fear is that contagion will spread to other European Union countries such as Portugal, Italy, and Spain.  That fear contributes to a “flight-to-quality” that helps US interest rates.

Greece's financial system may crumble next....
Greece’s financial system may crumble next….

International markets are helping US interest rates remain low but the domestic picture is less certain.  We know that the recent employment numbers have been fairly robust and that wages are rising in the US.  Assuming this trend continues the Fed will need to raise short-term interest rates in order to curb inflationary pressure.  That said, there is growing skepticism regarding the outlook for the economy.

This morning’s report on manufacturing and capacity utilization showed continued weakness in the manufacturing sector of the economy.  This is likely a consequence of a stronger US dollar and lower exports.

Later this week we’ll get the Fed’s latest monetary policy statement (Wednesday).  The Fed is not expected to raise short term interest rates this week but they may provide clarity on when they intend on starting that exercise.  On Thursday we’ll get the Consumer Price Index from the Labor Department which will reveal whether inflationary pressure is growing.

We’ll begin the week by floating to see if there is any follow through regarding the Greece storyline.

Current Outlook: floating

Mortgage Rate Update June 8, 2015

Mortgage rates had a tough run last week.  They have increased by ~.25% in the past week and a half.  Yields on US government bonds suffered the worst sell-off in over two years during the same timeline.

In case you missed it Friday’s all-important jobs report showed that the US economy created 280,000 new jobs during the month of May.  This was better than expectations and the highest reading since December of last year.  With the exception of March the US economy has added at least 200,000 new jobs each month for the past year.

jobs-report-6-5-15

Also embedded in the jobs report is information about average hourly earnings.  This part of the report showed that wages increased by more than expected last month which is an unwelcome sign for inflation and therefore interest rates.  With another healthy month of job growth analysts think it is more likely that the Fed will begin to raise rates later this year (versus early next year).

The economic calendar for the week gets busy in the latter half.  We’ll get retail sales on Thursday along with initial jobless claims.  On Friday we’ll get the latest reading on the producer price index.  Inflation is the missing piece of the puzzle for the Fed to begin raising rates.  It will be interesting to see if the PPI shows any signs of accelerating.

From a technical perspective mortgage-backed bonds are trying to rebound after a very tough ride.  We’ll float for now to see if we can recoup some ground.

Current Outlook: floating

Mortgage Rate Update June 4, 2015

Mortgage rates are at the highest levels since November of 2014.  Interest rates around the globe have moved higher during the first half of this week.

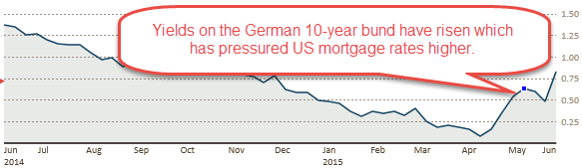
As we know changes in US mortgage rates tend to correlate to changes in yields on the US 10-year treasury note.  Lately, changes in the US 10-year treasury yield have correlated to changes in the yield on the German 10-year bund.  Therefore, changes to mortgage rates are closely correlated to changes in German interest rates.

6-4-10yr

As recently as April the yield on the German 10-year bund was ~.10%.  Yesterday it touched as high as .99%.  Over that time mortgage rates have increased by roughly .375%.

Yesterday the president of the European Central Bank stated that “the markets should get used to volatility.”  His comments caused interest rates around the globe to surge higher.

Let’s not forget that it’s jobs week and momentum can change with the single release of the all-important monthly report.  The markets are currently expecting 235,000 new jobs created in May.  Wednesday’s ADP private employer results showed 201,000 new jobs.  Typically speaking a number south of the expectation bodes well for rates and vice versa.

Given that rates have increased so sharply in the past three days I am going to recommend floating to see if we see a brief reprieve heading into next week.

Current Outlook: floating

Mortgage Rate Update June 1, 2015

Mortgage rates are unchanged from late last week.

The technical pattern for mortgage-backed bonds (MBS’s) which I identified as a positive sign for mortgage rates last Thursday is breaking down this morning.  MBS prices are drifting below the supportive trend line which does not bode well for mortgage rates.

US Consumers remain hesitant to spend their extra dough.

What is putting pressure on interest rates?  Greece announced earlier today that they would be on time with their next interest payment due to the International Monetary Fund.  The ailing country is scheduled to repay €1.6 billion over the next couple weeks.  Assuming they make all payments it would likely put upward pressure on mortgage rates.

The economic calendar is jam packed with significant information this week.   Earlier today the Commerce Department released its monthly personal spending report.  It showed that despite lower gasoline prices US consumers remain cautious.  This is not terribly surprising given that we got soft consumer confidence figures last week.

Also embedded in the report is the Fed’s favorite gauge of inflation known as the Personal Consumption Expenditure Price Index.  It showed that inflation continues to be below 2% which will prevent the Fed from hiking short-term rates soon.  Later this week we get the latest jobs report.

Given that the positive technical trading patterns have broken down I am inclined to recommend locking.

Current Outlook: locking

Mortgage Rate Update May 28, 2015

Mortgage note rates are mostly unchanged from the beginning of the week but the accompanying closing costs are slightly less.

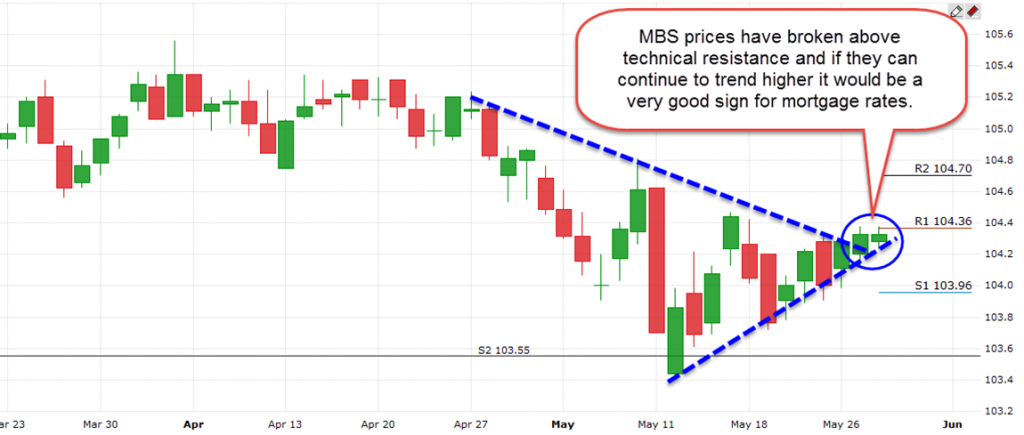
On Tuesday I highlighted the technical trading patterns that were evident in the mortgage-backed bond (MBS) market (CLICK HERE to review).  Currently MBS prices have tentatively broken above technical resistance which is a positive sign for the direction of mortgage rates.  However, it is premature to declare a victory.  Stay tuned….

05-28-MBS

More positive news for the housing market today.  According to the National Association of Realtors the number of pending sales rose by 14% from the same time last year.  From March to April they rose 3.4%, the highest one month increase in 9 years.

Tomorrow the financial markets will absorb the latest estimate of first quarter GDP and consumer sentiment.  If you’ll recall the US economy actually contracted in the first quarter as a result of the severe winter weather in the northeast.  Bad news for the economy is often good news for mortgage rates.

For now I will recommend a floating bias but should MBS prices retreat back below the aforementioned technical resistance we’ll need to shift to locking.

Current Outlook: floating

Mortgage Rate Update May 26, 2015

Mortgage rates are unchanged from late last week.

It’s a busy Tuesday morning in the financial markets.  With the week shortened by Memorial Day the economic calendar is dense.

In case you missed it Standard & Poor’s (S&P) released its latest version of the Case-Shiller Home Price Index.  The report showed continued home price appreciation across the country.  Here in Portland home prices increased by approximately 7% on a year-over-year basis.  Asked as to whether or not consumers should fear a “bubble” in housing S&P managing director David Blitzer commented, “I would describe this as a rebound in home prices, not bubble and not a reason to be fearful.”

According to the Commerce Department sales of new homes rose by more than expected in April.  Lastly, the Federal Housing Finance Agency (FHFA) released their latest reading on home prices.  It showed that home prices rose by 5.0% in a year-over-year basis ending in March.  The FHFA index uses purchase-only transactions that are financed by Fannie Mae or Freddie Mac secured loans.

05-26-15

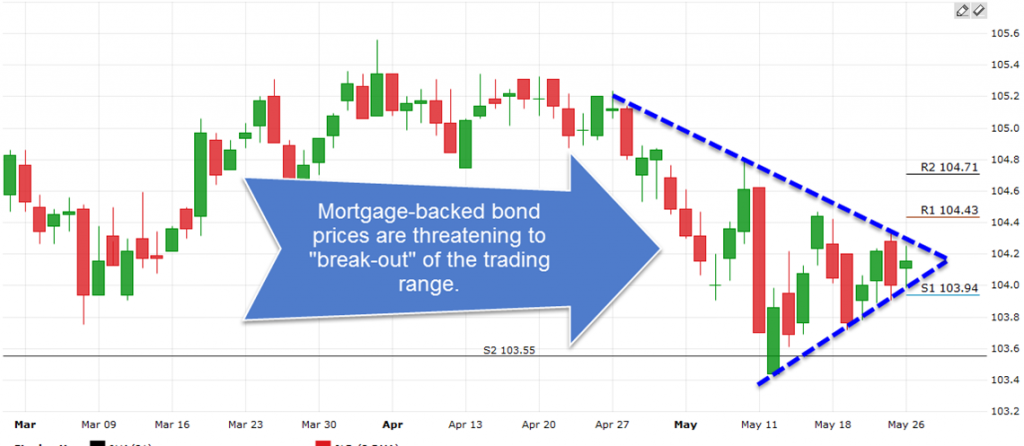
From a technical perspective conditions in the mortgage-backed bond (MBS) market look concerning.  The MBS trading range has converged over the past 10 days and are headed for a single point.  When we see this pattern we grow concerned about a “break-out” which is when prices move sharply higher or lower.  We will need to keep a close eye on things over the next couple days.

Current Outlook: safe play is to lock